Using Break-Even Analysis to Make Decisions (Cambridge International IGCSE Business)
Break-even analysis and decision-making
Spec point — "use break-even analysis to help make decisions: effect of changes in price, changes in fixed costs, changes in variable cost per unit"
Break-even analysis and decision-making
-
Break-even calculations are a useful tool for a business to use in deciding how much to produce and calculating estimated levels of profit
-
It is particularly useful for communicating with stakeholders, including investors or lenders
- Knowing when the business will break-even or how much profit it is expected to make may attract or deter shareholders *from investing in the business
-
Break-even analysis provides a basis for informed decision-making
-
It helps the business to assess the costs and expected returns of new projects and expansion plans
- By considering the break-even point, businesses can assess the potential risks and rewards associated with different decisions
-
Ways break-even is used in decision-making
| Use | How break-even analysis helps |
|---|---|
| Assessing profit or loss | - Shows the minimum sales needed to cover all costs and avoid losses - This helps the business set realistic profit targets |
| Managing costs | - Helps identify fixed and variable costs clearly - This allows the business to understand spending and cut unnecessary expenses |
| Pricing decisions | - Supports pricing by calculating the minimum price required to cover costs and achieve the desired profit |
| Financial planning | - Acts as a guide for setting realistic sales targets and planning future spending |
| Redrawing the graph with changes | - Demonstrates how changes in costs, prices, or sales volume affect the break-even point - This helps assess risks such as price increases or new competition |
| Performance monitoring | - Provides a benchmark to compare actual sales and costs - This helps the business measure progress and financial health |
Changes to break-even variables
Spec point — "use break-even analysis to help make decisions: effect of changes in price, changes in fixed costs, changes in variable cost per unit"
Changes to break-even variables
- Changing any of the variables of break-even (selling price, variable cost per unit or total fixed costs) changes the break-even point and level of profit it can expect to achieve
Increased selling price
- An increase in the selling price reduces the break-even point
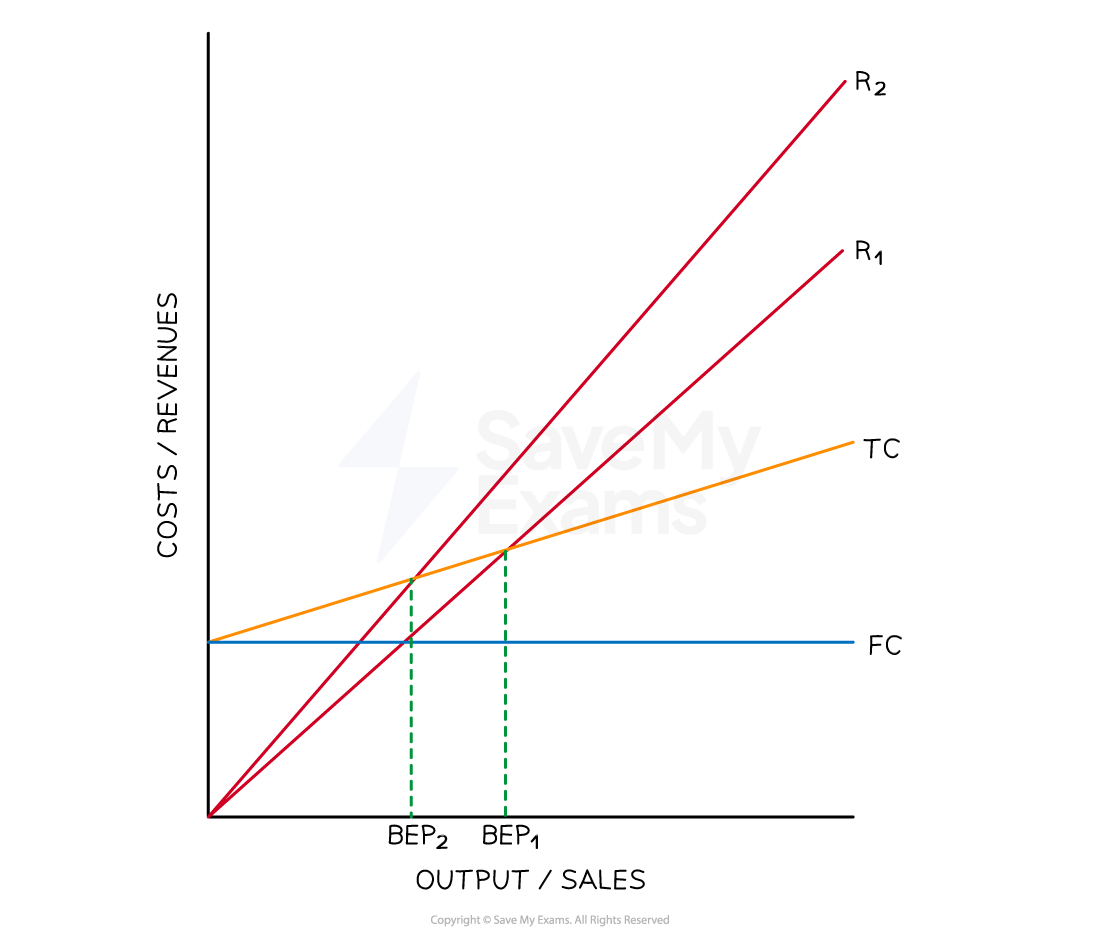
- An increase in the selling price increases revenue at each level of output from R1 to R2
- The break-even point falls from BEP1 to BEP2
- Profit on each unit of output greater than the break-even point is increased
Decreased selling price
- A decrease in the selling price increases the break-even point
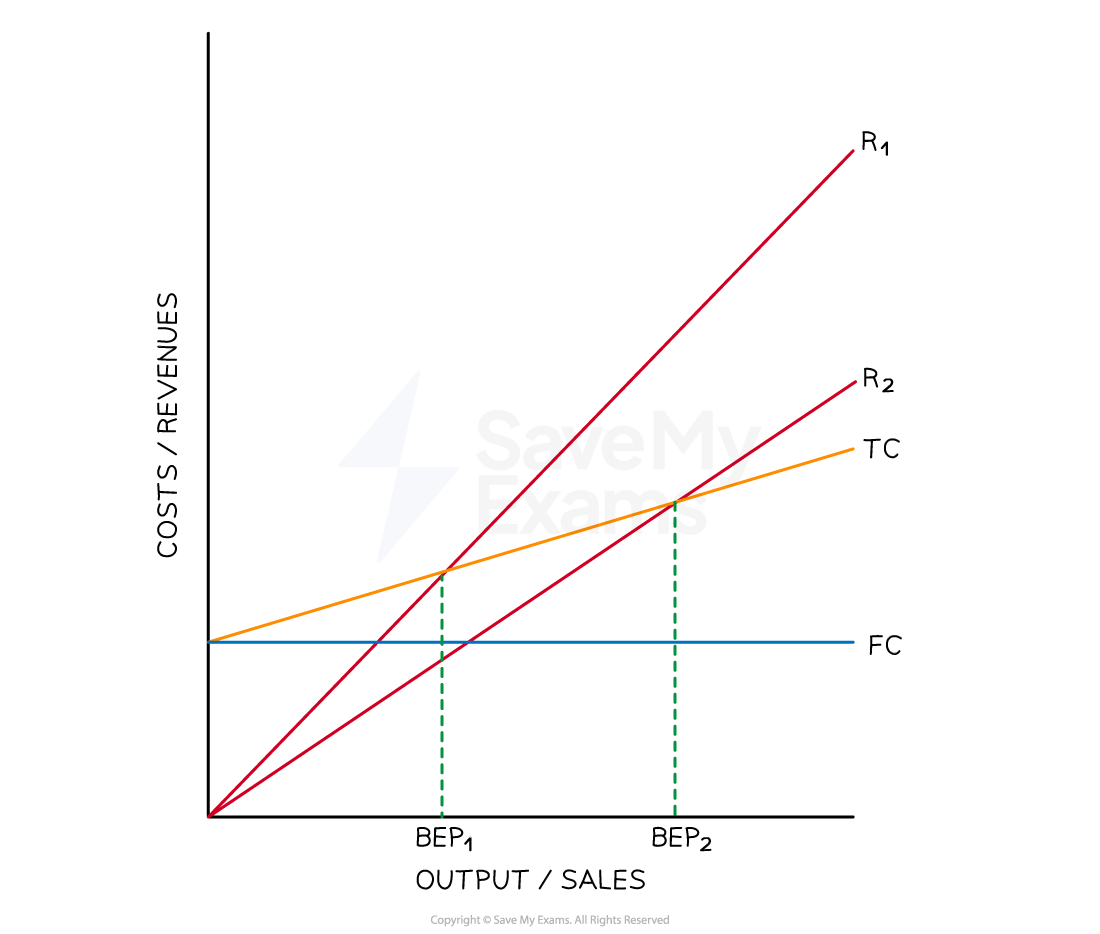
- A decrease in the selling price reduces revenue at each level of output from R1 to R2
- The break-even point rises from BEP1 to BEP2
- Profit on each unit of output greater than the break-even point is decreased
Increased variable costs
- An increase in variable costs increases the break-even point
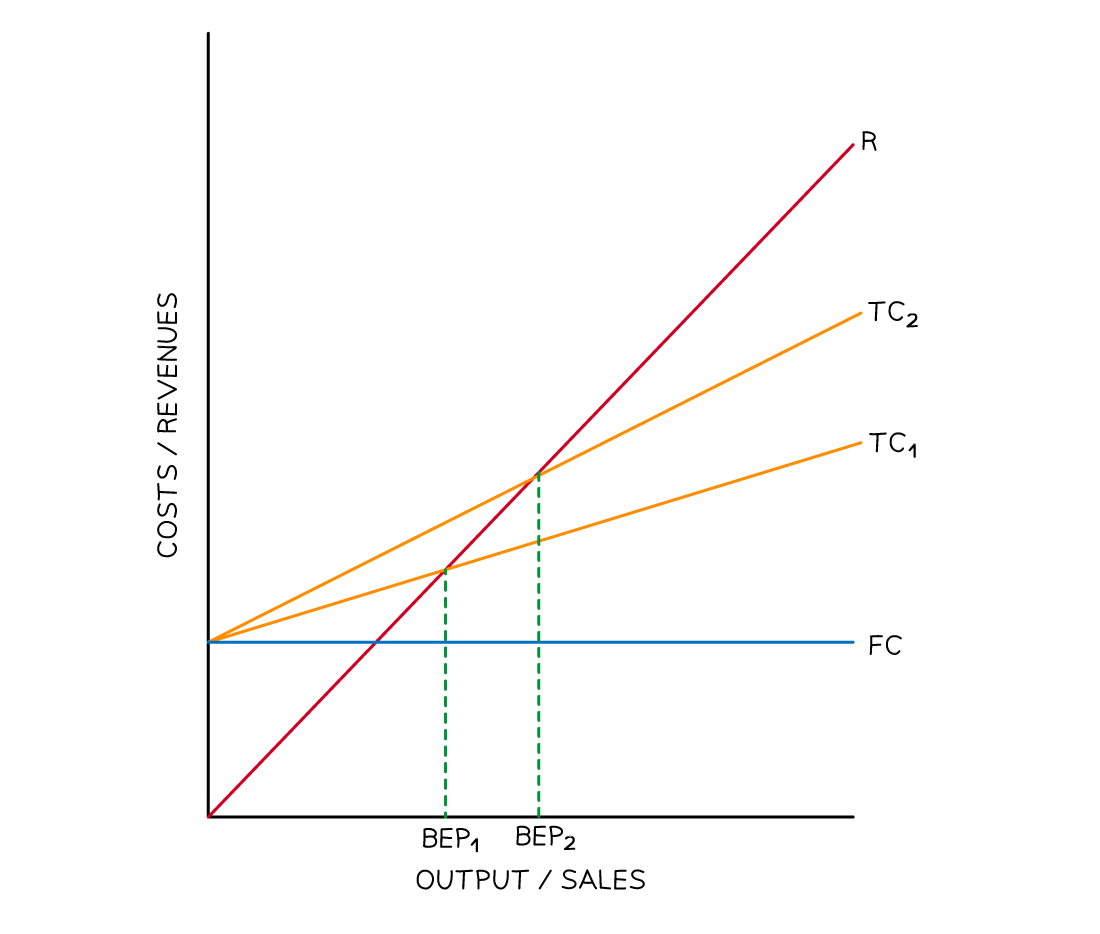
- An increase in variable costs increases total costs at each level of output from TC1 to TC2
- The break-even point increases from BEP1 to BEP2
- Profit on each unit of output greater than the break-even point is decreased
Decreased variable costs
- A decrease in variable costs decreases the break-even point
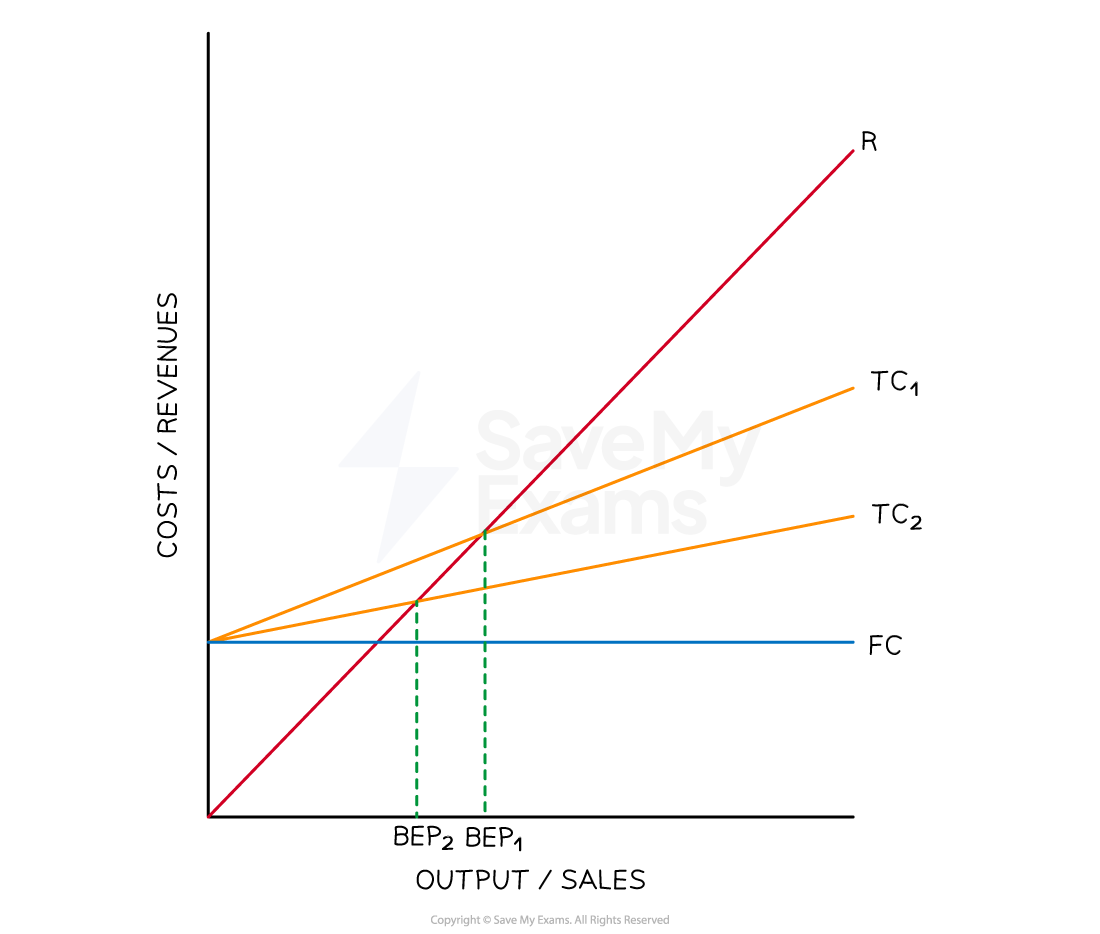
- A decrease in variable costs decreases total costs at each level of output from TC1 to TC2
- The break-even point falls from BEP1 to BEP2
- Profit on each unit of output greater than the break-even point is increased
Increased fixed costs
- An increase in fixed costs increases the break-even point
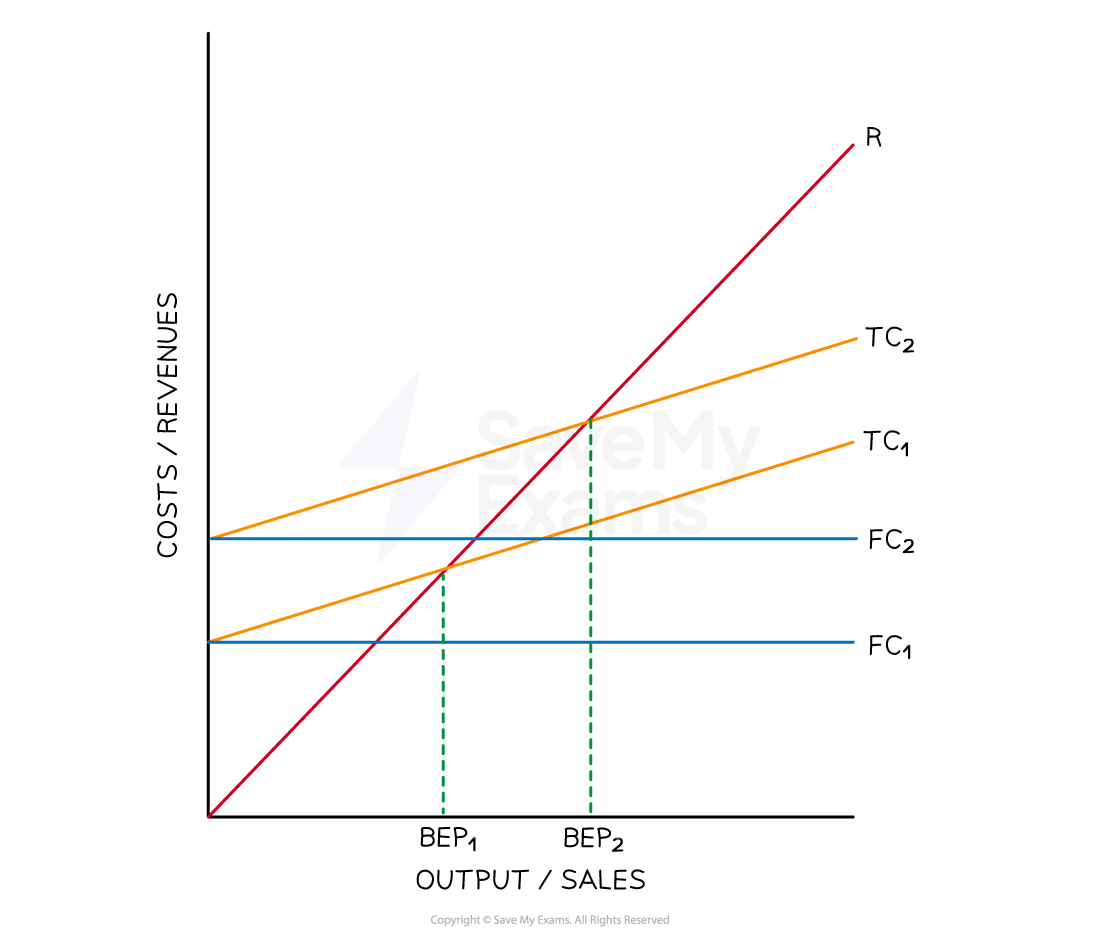
- An increase in fixed costs increases total costs at each level of output from TC1 to TC2
- The break-even point increases from BEP1 to BEP2
- Profit on each unit of output greater than the break-even point is decreased
Decreased fixed costs
- A decrease in fixed costs decreases the break-even point
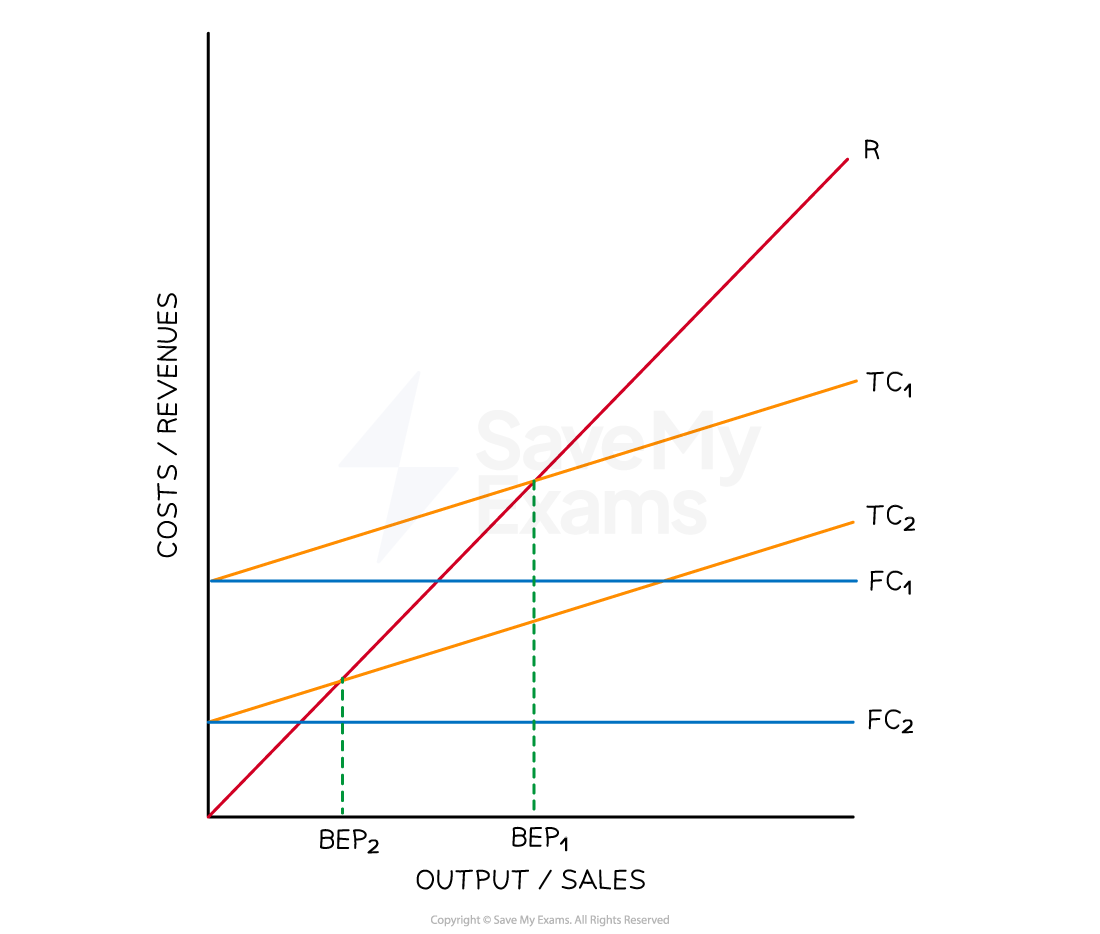
- A decrease in fixed costs reduces total costs at each level of output from TC1 to TC2
- The break-even point falls from BEP1 to BEP2
- Profit on each unit of output greater than the break-even point is increased
Exam Hint Strengthen your answers by linking changes in price, costs or sales volume to shifts in the break-even point and margin of safety – this application gains higher marks
Limitations of break-even analysis
- Break-even analysis provides valuable insights into the financial viability and performance of a business
- The sooner a business can reach break-even point, the more likely it is to survive and make a profit
- However, there are several limitations to the use of break-even analysis
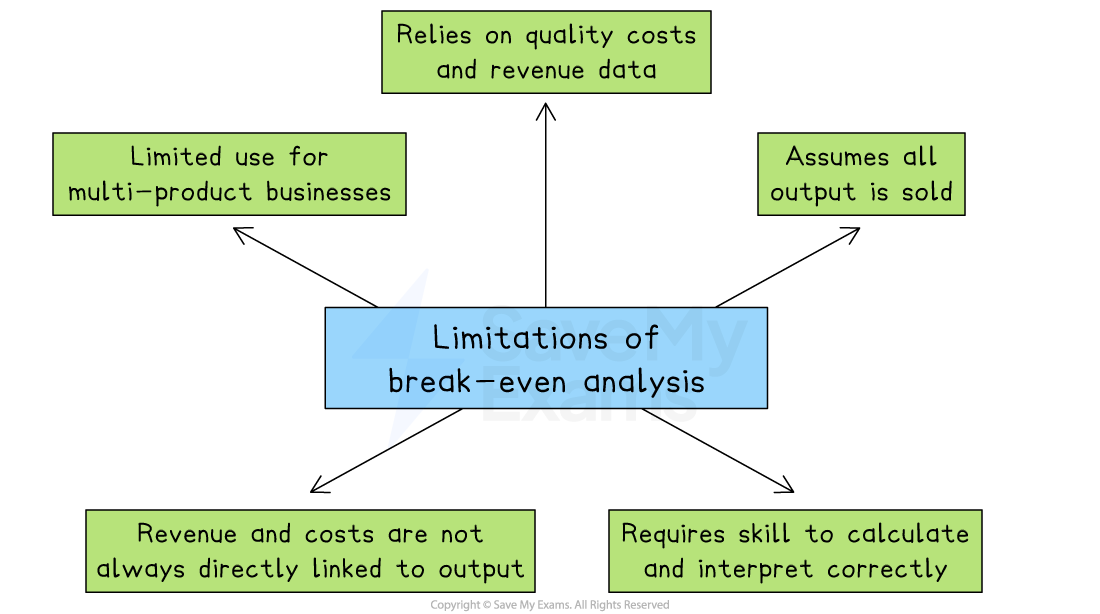
Limitations of break-even analysis include the assumption that all output is sold and its limited usefulness for multi-product businesses
1. Limited use for multi-product businesses
- Break-even analysis works best for businesses that sell one product
- If a business sells many products with different prices and profit margins, it is difficult to calculate a single break-even point that applies to all of them
2. Relies on quality costs and revenue data
- The results are only accurate if the data used is correct
- If the business uses outdated or incorrect cost or revenue figures, the break-even point will be misleading
3. Assumes all output is sold
- Break-even analysis assumes that everything produced is sold with no leftover stock
- In reality, some products may not sell, which can make the analysis too optimistic
4. Revenue and costs are not always directly linked to output
- The model assumes that costs and revenue change in a straight line as output increases
- However, in real life, discounts, bulk purchasing or changing raw material costs can affect this relationship.
5. Requires skill to calculate and interpret correctly
- To get useful results, the business must understand how to calculate and read break-even charts and data
- If the analysis is done poorly, it can lead to wrong decisions
Was this revision note helpful?