Identifying & Classifying Costs (Cambridge International IGCSE Business)
Introduction to costs
-
Businesses incur a range of costs
- Examples include purchasing raw materials, paying staff salaries and wages and paying utility bills such as electricity
-
These costs can be classified as follows:
- Fixed costs
- Variable costs
- Total costs
- Average costs
Fixed costs
Spec point — classify and calculate costs using examples, e.g. fixed, variable, average and total
-
Fixed costs (FC) are costs that do not change as the level of output changes
- These have to be paid whether the output is zero or 5000 units
- Examples include rent, management salaries, insurance and bank loan repayments
- Fixed costs can be plotted on a graph as a horizontal line
- The fixed costs for this firm are $4,000 at all levels of output
Variable costs
-
Variable costs (VC) are costs that are directly linked to output
- They increase as output increases and vice versa
- Examples include raw material costs and wages of workers directly involved in production
Graphical representation of total variable costs
- Variable costs are plotted on a graph as an upwards sloping line, starting at 0
Total costs
- The total cost is the sum of the variable and fixed costs
- Total costs are calculated using the formula
Graphical representation of total costs
- The total costs cannot be 0, as all firms have some level of fixed costs
- Total costs are plotted on a graph as an upwards sloping line, parallel to the variable costs, starting at the level of fixed costs
Average costs
-
The average cost is the typical cost of producing one unit of output
- It is sometimes called the unit cost
-
As a firm grows, it is able to increase its scale of output generating efficiencies that lower its average total costs (AC) of production
- These efficiencies are called economies of scale
Graphical representation of average costs
-
As a firm continues increasing its scale of output, it will reach a point where its average total costs (AC) start to increase
- These inefficiencies are called *diseconomies of scale *
Exam Hint Always set out each step when calculating fixed, variable, total and average costs. Even if your final figure is wrong, clear working can earn method marks
Using cost data to make decisions
- Businesses can use cost data to make data-driven business decisions
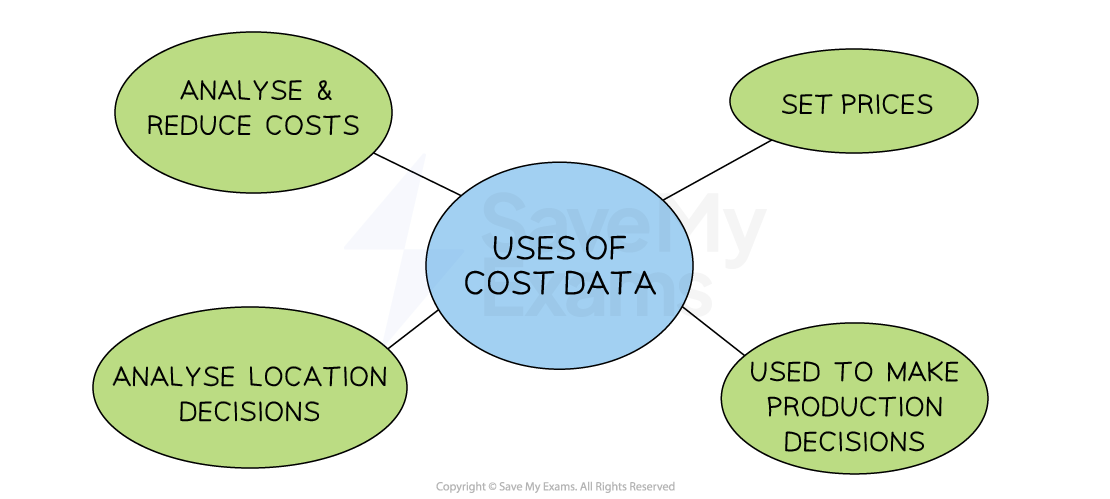
Accurate cost data can help a firm to be more precise in its price setting and production decisions
1. To reduce costs
-
Accurate cost data helps a business see if costs are too high
-
Reducing costs is a key way to increase profit
- Fixed costs can be reduced by moving to cheaper premises, lowering staff salaries, cutting promotional spending or using cheaper utility suppliers
- Variable costs can be lowered by buying cheaper or bulk raw materials, or outsourcing delivery
-
Businesses must consider how cost-cutting affects customer service, product quality and delivery speed
- Paying lower wages may lead to less experienced or skilled staff
- Cheaper materials might reduce product quality
2. To set prices
-
Costs are important when deciding the selling price.
-
They directly affect how much profit a business makes.
- For example, if a cake costs $3 to make and the business wants to make a $1 profit on each cake, it must sell them for $4
3. To make production decisions
-
If production costs are higher than revenue, the business will make a loss
- The business must decide whether to keep or stop making it
-
This depends on factors including
- Whether it’s a new product, with sales likely to rise
- Whether fixed costs will need to be paid, even if production stops
4. To make location decisions
- Renting or buying premises is a major cost
- Some areas are cheaper than others
- Businesses must compare these savings to other factors like transport, closeness to customers and available workers
Was this revision note helpful?