Completing & Interpreting Cash Flow Forecasts (Cambridge International IGCSE Business)
Completing cash flow forecasts
Spec point — "amend or complete a simple cash flow forecast Note: candidates will not be assessed on constructing a cash flow forecast."
Completing cash flow forecasts
- A business must first gather information about all cash inflows and cash outflows it expects to encounter over the period
- The following steps should then be taken to construct the cash flow forecast
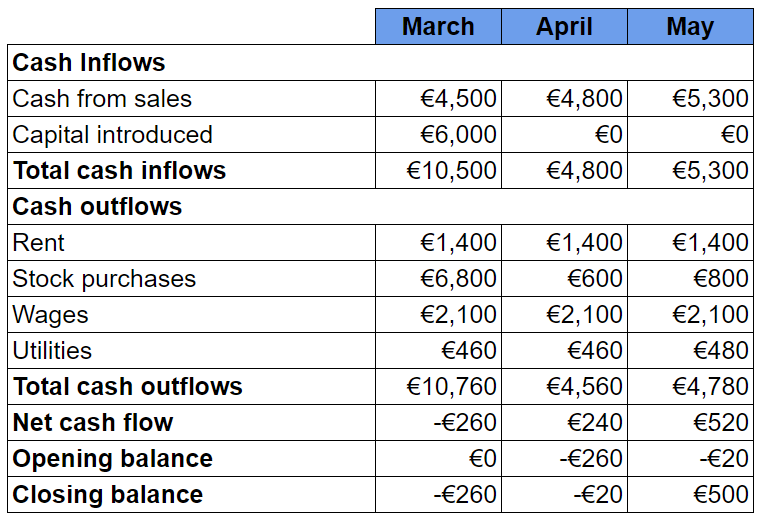
Step 1 – Calculate total cash inflows
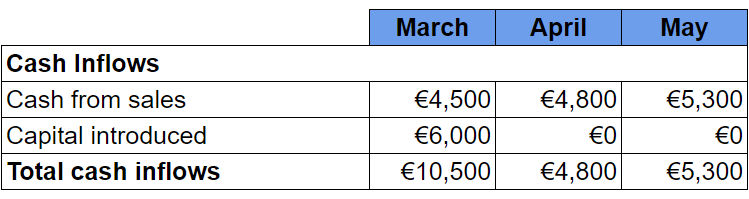
- In this instance, the business expects to receive cash inflows from sales in March, April and May
- Owners' capital of €6,000 will be introduced in March
- The total for each month is calculated by adding cash from sales to capital introduced
Step 2 – Calculate total cash outflows
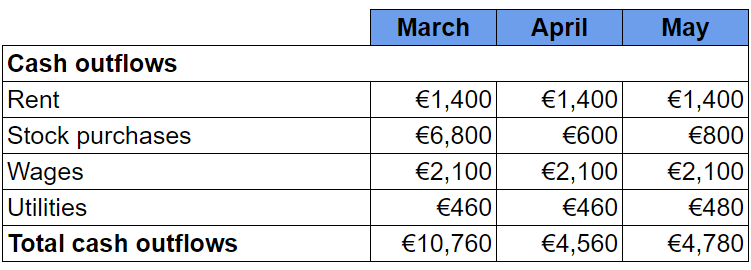
- In this instance, the business expects to pay rent of €1,400 in March, April and May
- It will purchase a significant amount of stock in March with smaller amounts in April and May
- Wages are expected to be €2,100 in each month
- Utilities of €460 will be paid in March and April, increasing to €480 in May
- Total cash outflows each month is calculated by adding these together
Step 3 – Calculate net cash flows
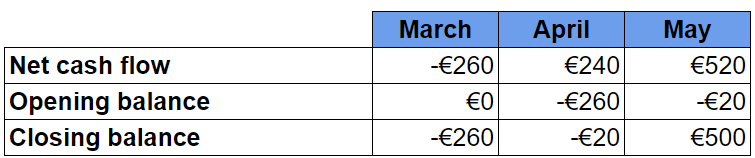
- The net cash flow is calculated by subtracting total cash outflows from total cash inflows
-
In March the net cash flow is €10,500 - €10,760 = €(260)
- Net cash flow is negative as cash outflows are greater than cash inflows
-
In April the net cash flow is €4,800 - €4,560 = €240
-
In May the net cash flow is €5,300 - €4,780 = €520
- In both months, net cash flow is positive as cash inflows are greater than cash outflows
Step 4 – Calculate opening and closing balances
- The opening balance is the previous month’s closing balance carried forward
- The closing balance is calculated by adding the net cash flow to the opening balance
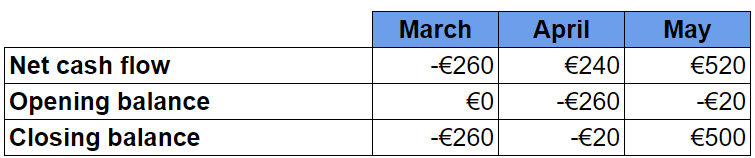
- In March the opening balance of €0 is added to the net cash flow of €(260) to leave a closing balance of €(260)
- In April the closing balance from March is carried forward to become its opening balance of €(260)
- This opening balance is added to April's net cash flow of €240 to leave a closing balance of €(20)
- In May the closing balance from April is carried forward to become its opening balance of €(20)
- This opening balance is added to May's net cash flow of €520 to leave a closing balance of €500
The complete cash flow forecast
Worked Example Here is a simple three-month cash flow forecast for a small seaside café
March April May Cash Inflows Sales 46,000 54,000 61,000 Cash Outflows Inventory 13,000 13,000 13,000 Wages 28,000 28,000 Miscellaneous 3,500 4,000 4,000 Total Cash Outflows 45,000 48,000 Net cash flow 1,500 9,000 Opening balance 4,000 5,500 14,500 Closing balance 14,500 30,500 Complete the cash flow forecast to show
a. Total cash outflows for March
b. Closing balance for March
c. Wages for May
d. Net cash flow for May
(4)
Step 1: Add all of March's cash outflows to calculate the total
[1]
Step 2: Add the opening balance to the net cash flow to calculate March's closing balance
[1]
Step 3: Subtract inventory and miscellaneous outflows from total cash outflows to calculate wages
[1]
Step 4: Subtract total cash outflows from total cash inflows to calculate net cash flow
[1]
Exam Hint Always set out your calculations clearly – show how you worked out inflows, outflows, net cash flow, and balances. Even if your final figure is wrong, you can still gain marks for the working
Interpreting cash flow forecasts
Spec point — interpret a simple cash flow forecast
- Once a cash flow forecast has been constructed, managers may be able to use it to make financial decisions
- Overall, this cash flow forecast supports an application for the business to borrow £6,000 in March to cover the initial low inflows, significant outflows and negative net cash flow
- It may also arrange a short-term overdraft to cover negative closing balances in March and April
- Healthy sales mean that from May, inflows are greater than outflows and the business has a positive net cash flow
Overcoming cash flow problems
Spec point — "how a short-term cash flow problem may be overcome: overdraft, delaying supplier payments, asking customers to pay more quickly, delay purchase of non-current assets"
Overcoming cash flow problems
-
The cash flow forecast example above identifies a cash flow problem in March and April where the closing balance is negative
-
It has a range of ways to solve this issue to prevent insolvency
- The most suitable method may be to arrange a flexible, short-term overdraft facility with its bank
Ways to solve cash flow problems
| Method | Explanation |
|---|---|
| Reduce the credit period offered to customers | - Collecting money owed from customers more quickly - However, customers may move to competing businesses that offer better credit terms |
| Ask suppliers for an extended repayment period e.g an extension from 60 to 90 days | - The business can use cash it would have paid to suppliers for other purposes - Suppliers may be unwilling to extend credit terms |
| **Make use of overdraft facilities or short-term loans | - The business can spend more money than it has in its bank account - Banks may be reluctant to lend to businesses with cash-flow problems |
| Sell off excess stock | - Less liquid current assets will be converted into cash - Storage and security costs may also be reduced - Stock may need to be sold at a low price to attract sales |
| Sell assets and lease fixed assets instead | - The business will continue to have the use of assets but must make regular payments to the leasing company |
| ** Introduce new capital and reduce **drawings from the business | - New capital may be** introduced by the owner or from additional investors - This may result in the dilution of control of the business |
-
A business can also have too much cash
- If it holds large amounts of cash, it may miss out on the benefits of investing it in fixed assets or savings
- This may represent a significant opportunity cost, *especially when interest rates are high
Was this revision note helpful?
Build on this topic