The Trial Balance (Edexcel IGCSE Accounting)
Uses & Limitations of a Trial Balance
Spec point —
IGCSE_ACCOUNTING:S3.149
What is a trial balance?
-
A trial balance is a statement which lists all accounts and their balances on a particular date
- Each balance is placed either in the debit column or in the credit column
-
The totals of the debit and credit columns are calculated
- The totals should be equal
-
A trial balance is not part of the double entry system
-
The balance for the inventory account will always be the opening balance
- This is because the current inventory is contained within the purchases account
- This is dealt with once the balances are transferred to the income statement
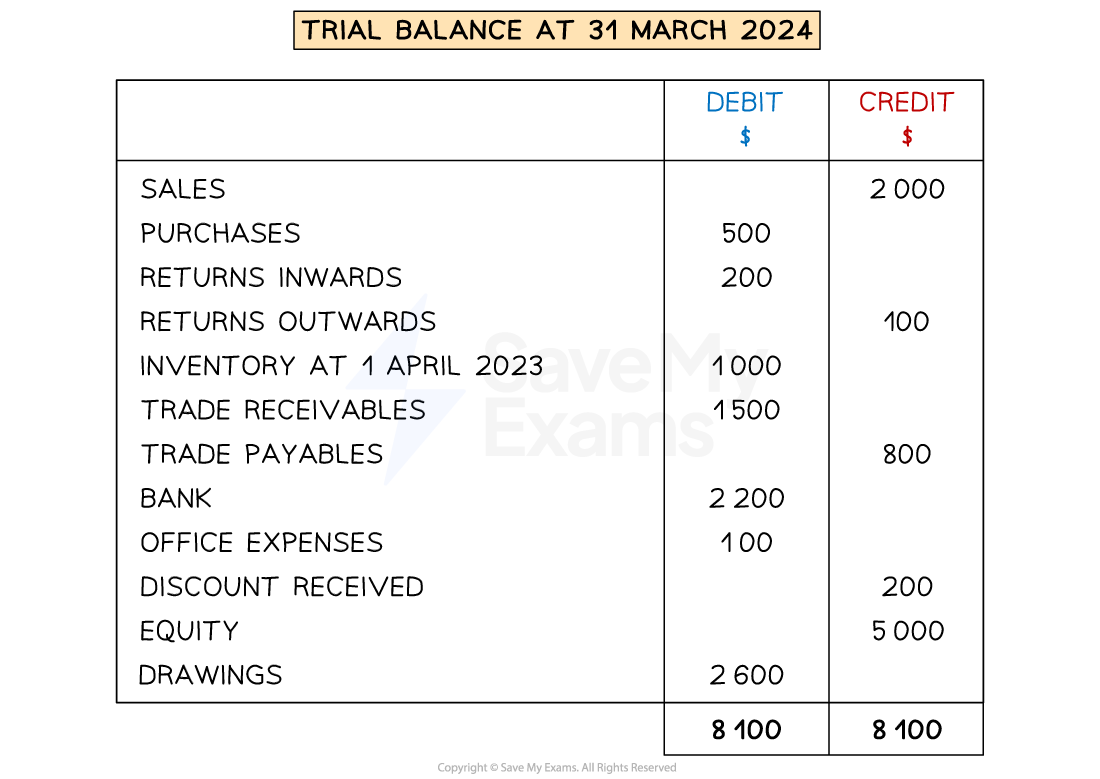
Example of a trial balance
What are the uses of a trial balance?
-
A trial balance is used to check for arithmetic errors in the ledger accounts
- If the balance of a ledger account has been miscalculated, it is likely that the totals in the trial balance will not be equal
-
Preparing a trial balance helps with the preparation of financial statements
- All the balances are in one place
What are the limitations of a trial balance?
-
Not all errors are identified by a trial balance
- The totals may be equal despite there being errors
-
You will need to use other measures to locate errors
- Such as bank reconciliation statements and control accounts
Preparing a Trial Balance
Spec point —
IGCSE_ACCOUNTING:S3.148
How do I prepare a trial balance?
-
You will likely be given a list of accounts and balances
-
STEP 1 Identify whether each account should have a debit or a credit balance
- The table below gives a summary of the different accounts
-
STEP 2 Check that the total of the debits is equal to the total of the credits
-
STEP 3 Write each account in the trial balance and put the balance in the correct column
-
STEP 4 Total each column
| Accounts with debit balances | Accounts with credit balances |
|---|---|
| Purchases | Purchases returns (returns outwards) |
| Sales returns (returns inwards) | Sales (revenue) |
| Other expenses | Other income |
| Trade receivables | Trade payables |
| Bank | Bank overdraft |
| Other assets (Including inventory, vehicles, machinery, etc) | Other liabilities (Including bank loan, mortgage, etc) |
| Drawings | Equity |
| Provision for depreciation | |
| Provision for doubtful debt |
Exam Hint Check the totals agree before you write any accounts in the trial balance. This will help you spot any mistakes before you write anything in the trial balance.
How do I amend a trial balance?
-
You could be given a trial balance which contains errors
- The balances could also be in the wrong columns
-
STEP 1 Correct the errors to find the correct balances for each account
-
STEP 2 Double-check whether each account has been correctly identified as a debit or a credit
-
STEP 3 Complete a corrected trial balance
- The totals will be equal
Worked Example Dimitri is a sole trader. He has prepared a trial balance on 31 March 2024. However, it contains errors.
Dimitri Trial Balance at 31 March 2024
Debit
$Credit
$Sales 35 471 Purchases 17 714 Returns outwards 1 407 Discount received 1 895 Rent paid 5 321 General expenses 2 087 Office equipment at cost 20 000 Provision for depreciation of office equipment 4 580 Trade receivables 9 710 Trade payables 3 980 Inventory 7 060 Bank overdraft 450 Equity at 1 April 2023 20 869 Drawings 8 760 67 933 71 371 Dimitri has included the value of the inventory on 31 March 2024, the value of the inventory on 31 March 2023 was $2 000 lower than this value. Prepare a corrected trial balance at 31 March 2024.
Answer
STEP 1 - Correct any amounts
The value of inventory should be for 31 March 2023
- $7060 - $2000 = $5060
STEP 2 - Identify whether the balances should be debits or credits
The following should have debit balances:
- Purchases
- Rent paid
- General expenses
- Office equipment at cost
- Trade receivables
- Inventory
- Drawings
All other items should have credit balances
STEP 3 - Prepare the corrected trial balance
Final answer: Dimitri Corrected Trial Balance at 31 March 2024
Final answer: Debit
Final answer: $**Final answer: Credit
Final answer: $Final answer: Sales Final answer: 35 471 Final answer: Purchases Final answer:** 17 714 Final answer: Returns outwards Final answer: 1 407 Final answer: Discount received Final answer: 1 895 Final answer: Rent paid Final answer: 5 321 Final answer: General expenses Final answer: 2 087 Final answer: Office equipment at cost Final answer: 20 000 Final answer: Provision for depreciation of office equipment Final answer: 4 580 Final answer: Trade receivables Final answer: 9 710 Final answer: Trade payables Final answer: 3 980 Final answer: Inventory Final answer: 5 060 Final answer: Bank overdraft Final answer: 450 Final answer: Equity at 1 April 2023 Final answer: 20 869 Final answer: Drawings Final answer: 8 760 Final answer: 68 652 Final answer: 68 652
Was this revision note helpful?
Build on this topic