Business Objectives (Cambridge International IGCSE Business)
Exam board Cambridge International · IGCSEUpdated 2026-03-06
The importance of business objectives
- Business aims are the long-term aspirations of an organisation
- Business objectives are specific, measurable, achievable, relevant, and time-bound targets (SMART targets) that must be achieved to realise business aims
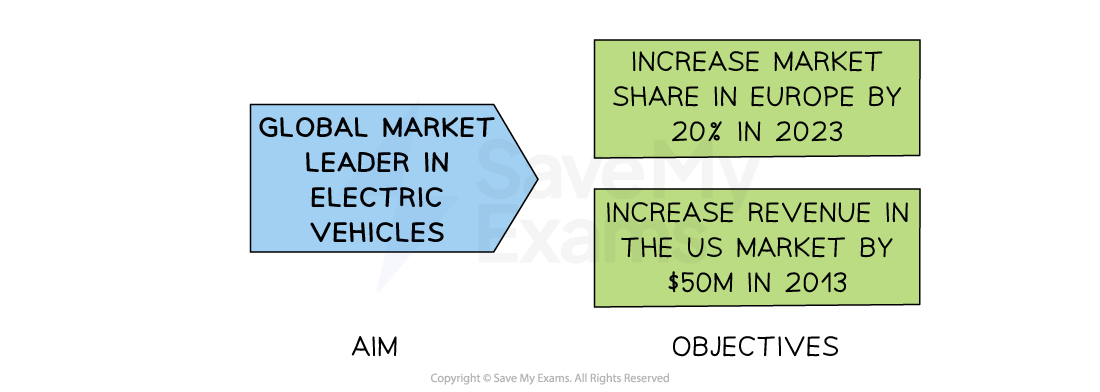
Objectives are derived from a business's overall aim
-
Every successful business needs to have clear aims and objectives that guide its operations and focus the efforts of all employees towards the same goal
- Aims and objectives are critical for businesses to function effectively and achieve long-term success
- A business aim may be to become the market leader in a particular industry
- The corresponding objectives may include increasing sales by 25% over the next three years, improving customer satisfaction by 15%, and expanding into new geographic markets
Benefits of setting business objectives
-
They give the business a clear sense of direction
- Everyone in the business knows what they are working towards, which helps managers make decisions and keeps employees focused on the same goals
-
They make it easier to measure success
- By setting a specific target (such as increasing sales by 10% in a year), a business can track its progress and see whether it is performing well or needs to make changes
-
They help motivate employees
- When staff understand what the business is trying to achieve and can see how their work contributes to that goal, they are more likely to feel engaged and work hard to reach it
Types of business objectives
Spec point — businesses can have several objectives, e.g. survival, growth, profit, market share
-
Objectives provide a focus or target for managers and employees
- Managers can determine how well the business or particular departments have performed over a period of time
- Employees may be rewarded for their progress towards meeting objectives
-
As businesses grow, their objectives often change over time
- For example, they may shift from survival and break-even to growth and profit maximisation
Common business objectives
| Objective | Explanation |
|---|---|
| Survival | - A common objective in the early stages of trading - 60% of UK start-ups fail within their first three years - Common reasons for failure include poor cashflow, low sales and unexpected costs |
| Growth | - Businesses often achieve growth by increasing sales - Persuading customers to buy products more often or in greater quantities to increase sales revenue and expand the business - Appealing to new market segments |
| Profit | - Ensuring sales revenue received is greater than business costs - This allows for f inancial security as a business and its owners can pay all the overheads and have some in reserve to pay for unexpected emergencies |
| Market share | - The percentage of the total market revenue that a single business or brand achieves - Costa had an 8% market share of 'out-of-home' coffee consumption in the UK in 2020 - If market share is increasing, it means that the firm is competing effectively with rivals |
Exam Hint Avoid suggesting that ‘making as much profit as possible’ is always the most likely objective of a business
- It often depends on economic conditions and the original aims of the owners
- Many entrepreneurs are more focused on helping groups in society than making money
- As markets can be very dynamic, objectives are very likely to change over time
Was this revision note helpful?
Build on this topic