The Petty Cash Book (Cambridge International IGCSE Accounting)
The petty cash book
What is a petty cash book?
-
A petty cash book is used to record transactions involving small amounts of cash
- The business will decide what they classify as small amounts of cash
- Exam questions commonly tell you to class transactions for anything up to $100 or $75 as petty cash transactions
-
A petty cash voucher is used to record the transaction when money is taken from the petty cash account
- It should state the amount and details
What is the layout of a petty cash book?
-
There is a date column and a details column
- These commonly appear once in the middle
-
The total received column on the debit side states the total amount received for each transaction
-
The total paid column on the credit side states the total amount paid for each transaction
-
There are analysis columns on the credit side to separate payments into different categories
- There are columns for the expense accounts and a column for the purchases ledger accounts
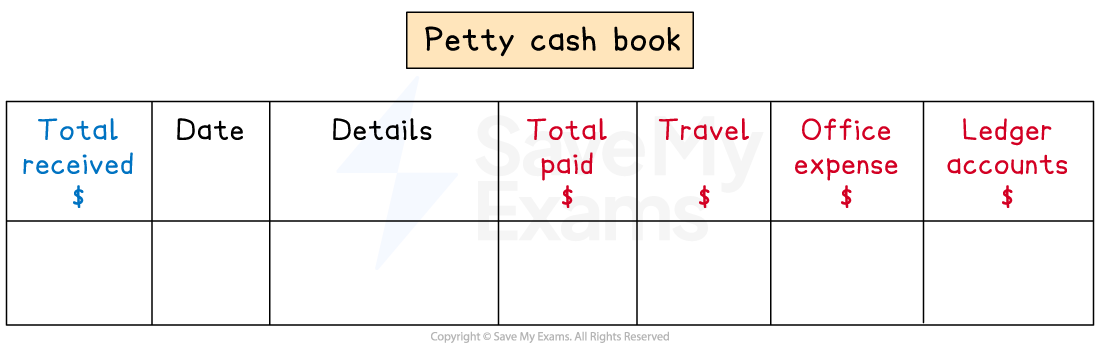
The layout of a petty cash book
How do I enter transactions into the petty cash book?
-
The opening balance is on the debit side
-
The debit side shows the cash receipts
- Small cash receipts from trade receivables
- Money transferred from the cash or bank account to top up the petty cash account
-
The credit side shows the cash payments
- Small cash payments for expenses
- Small cash payments to trade payables
-
When you enter a transaction onto the credit side
- You need to enter it in the appropriate analysis column(s)
- Put the total for that transaction in the total paid column
How do I balance the petty cash book?
-
Find the total for each column on the credit side
-
Underline the totals for the analysis columns
-
These balances then get transferred to the relevant ledger accounts
- You can transfer the total for each expense column rather than transfer each transaction separately
- The entries for ledger accounts will need to be entered into the individual ledger accounts
-
-
Find the difference between the total paid and the total received
-
Put this entry as balance c/d on the side with the smaller total
- This will usually be the credit side
-
-
Complete the balancing process for these two columns
-
Find the totals for the total received and total paid columns
-
Bring down the balance to the start of the next month
- The balance brought down will always be on the debit side
-
Worked Example Nazim is a sole trader. Nazim makes all payments of less than $75 by petty cash. Nazim ensures that there is exactly $150 in the petty cash account at the start of each month.
Below are the cash transactions for January 2024.
January 5 Paid taxi fare, $23 8 Paid cash, $45, to Jamie, a trade payable 13 Paid $25 for stationery 17 Received cash, $67, from Hawa, a trade receivable 25 Paid train fare, $51 30 Paid cash, $17, to Melody, a trade payable Enter these transactions into Nazim’s petty cash book. Balance the account and bring down the balance on 1 February 2024.
Total Received
$**Date Details Total Paid
$Travel
$Office expenses
**$Ledger accounts
$150 2024
Jan 1Balance b/d Answer:
- Total received
$150 + $67 = $217
- Total paid
$23 + $45 + $25 + $51 + $17 = $161
- Find the difference
$217 - $161 = $56
Total Received
$**Date Details Total Paid
$Travel
$Office expenses
$Ledger accounts
$150 2024
Jan 1Balance b/d Final answer: Jan 5 Final answer: Taxi fare Final answer: 23 Final answer: 23 Final answer: Jan 8 Final answer: Jamie Final answer: 45 Final answer: 45 Final answer: Jan 13 Final answer: Stationery Final answer: 25 Final answer: 25 Final answer: 67 Final answer: Jan 17 Final answer: Hawa Final answer: Jan 25 Final answer: Train fare Final answer: 51 Final answer: 51 Final answer: Jan 30 Final answer: Melody Final answer: 17 Final answer:** ** Final answer:** Final answer: 17 Final answer: 161 Final answer: 74 Final answer: 25 Final answer: 62 Final answer: Jan 31 Final answer: Balance c/d Final answer: 56 Final answer: 217 Final answer: 217 Final answer: 56 Final answer: Feb 1 Final answer: Balance b/d
The Imprest System
What is the imprest system?
-
The imprest system is used by businesses to ensure that the money in the petty cash account is equal to a set amount
- This amount is known as the imprest amount
- This is usually done at the start of each week or month
-
If the petty cash account is less than the imprest amount at the start of a period
- Then it will be topped up using the cash or bank account
-
If the petty cash account is higher than the imprest amount at the start of a period
- Then the excess can be deposited into the cash or bank account
-
The imprest amount will always be equal to:
- The current balance of the petty cash account
- Plus the total value of petty cash vouchers for the current period
- Minus the total amount of petty cash received
What are the advantages of using an imprest system?
- It sets a limit on the amount of cash which can be spent
- It helps managers monitor the amount of petty cash that is being spent
- It limits the amount of cash that could be mislaid or stolen
Exam Hint Read the question carefully to see whether you are asked to restore the imprest or not. Also, check when the imprest is restored.
Worked Example Mark maintains a petty cash account using the imprest system. The imprest amount, $200, is restored on the first day of every month.
During January 2024, Mark receives $50 from trade receivables, and the total of the petty cash vouchers for payments is $120.
Calculate how much cash is needed to restore the imprest on 1 February 2024.
Answer:
Find the net amount that left the petty cash account
$120 - $50 = $70
Final answer: $70 is needed to restore the imprest
Was this revision note helpful?
Build on this topic