Revaluation Method of Depreciation (Cambridge International IGCSE Accounting)
Revaluation depreciation
What is the revaluation method of depreciation?
-
The revaluation method of depreciation involves performing a valuation of assets at the end of the financial year to determine the reduction in value
-
This method is commonly used for assets of smaller value
- Such as loose tools, packing cases
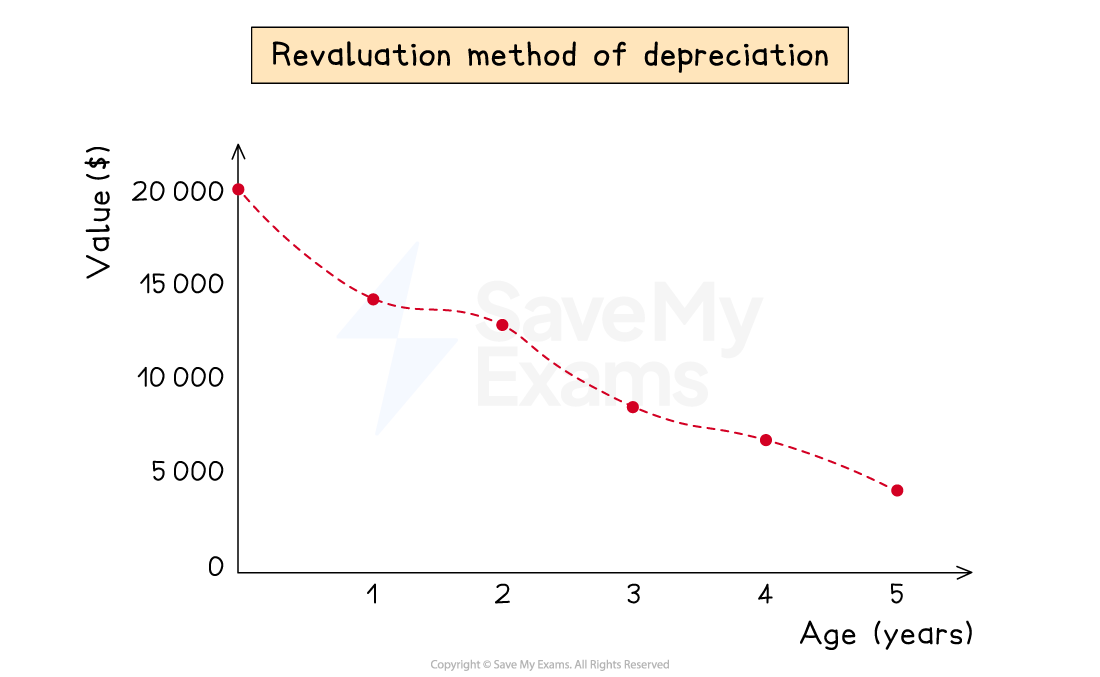
Example of an asset, which cost $20 000, being charged depreciation using the revaluation method each year
How do I calculate depreciation using the revaluation method?
-
A revaluation of the non-current asset will be given in the question
-
You need to identify two numbers:
- The net book value before the revaluation
- The net book value after the revaluation
-
The depreciation charge is the value before minus the value after
Worked Example Abi purchased fixtures and fittings for $5 000 on 1 March 2023. On 29 February 2024, at the end of the financial year, the fixtures and fittings were valued at $3 650.
Calculate the depreciation charged for the financial year ending on 29 February 2024.
Answer:
- Value before the revaluation is $5 000
- Value after the revaluation is $3 650
- Calculate the difference
$5 000 - $3 650 = $1 350
Was this revision note helpful?
Build on this topic