Income Statement (Cambridge International IGCSE Accounting)
Income statement for sole traders
What is the purpose of an income statement for a sole trader?
-
It is a statement prepared for a trading period to show the gross profit and the profit for the year
-
A financial year does not necessarily follow the calendar year from January to December
- For example, if a business commences trading on 1 July 2023 then the first financial year would run from 1 July 2023 to 30 June 2024
-
-
The income statement consists of two parts
- The trading section shows the calculation of the gross profit
- The profit and loss section shows the calculation of the profit for the year
-
The income statement is part of the double entry system of book-keeping
-
Debit entries to the income statement decrease profit
- These are usually the expenses
-
Credit entries to the income statement increase profit
- These are usually the sources of income
-
-
An income statement can sometimes be created like an account with a debit side and a credit side
-
This is called the horizontal format
-
The balancing figure will be the profit or loss
- Profit if it is on the debit side
- Loss if it is on the credit side
-
-
However, most businesses produce income statements as a statement using the vertical format
How do I complete the trading section of an income statement?
-
STEP 1 Calculate the total revenue and put the value in the far right column
- Revenue
- Less sales returns
-
STEP 2 Calculate the cost of sales and put the value in the far right column
-
Opening inventory
-
Add net purchases
- Purchases
- Less purchases returns
- Less goods for own use
- Add carriage inwards
-
Less closing inventory
-
-
STEP 3 Calculate the gross profit and put the value in the far right column
- Revenue
- Less cost of sales
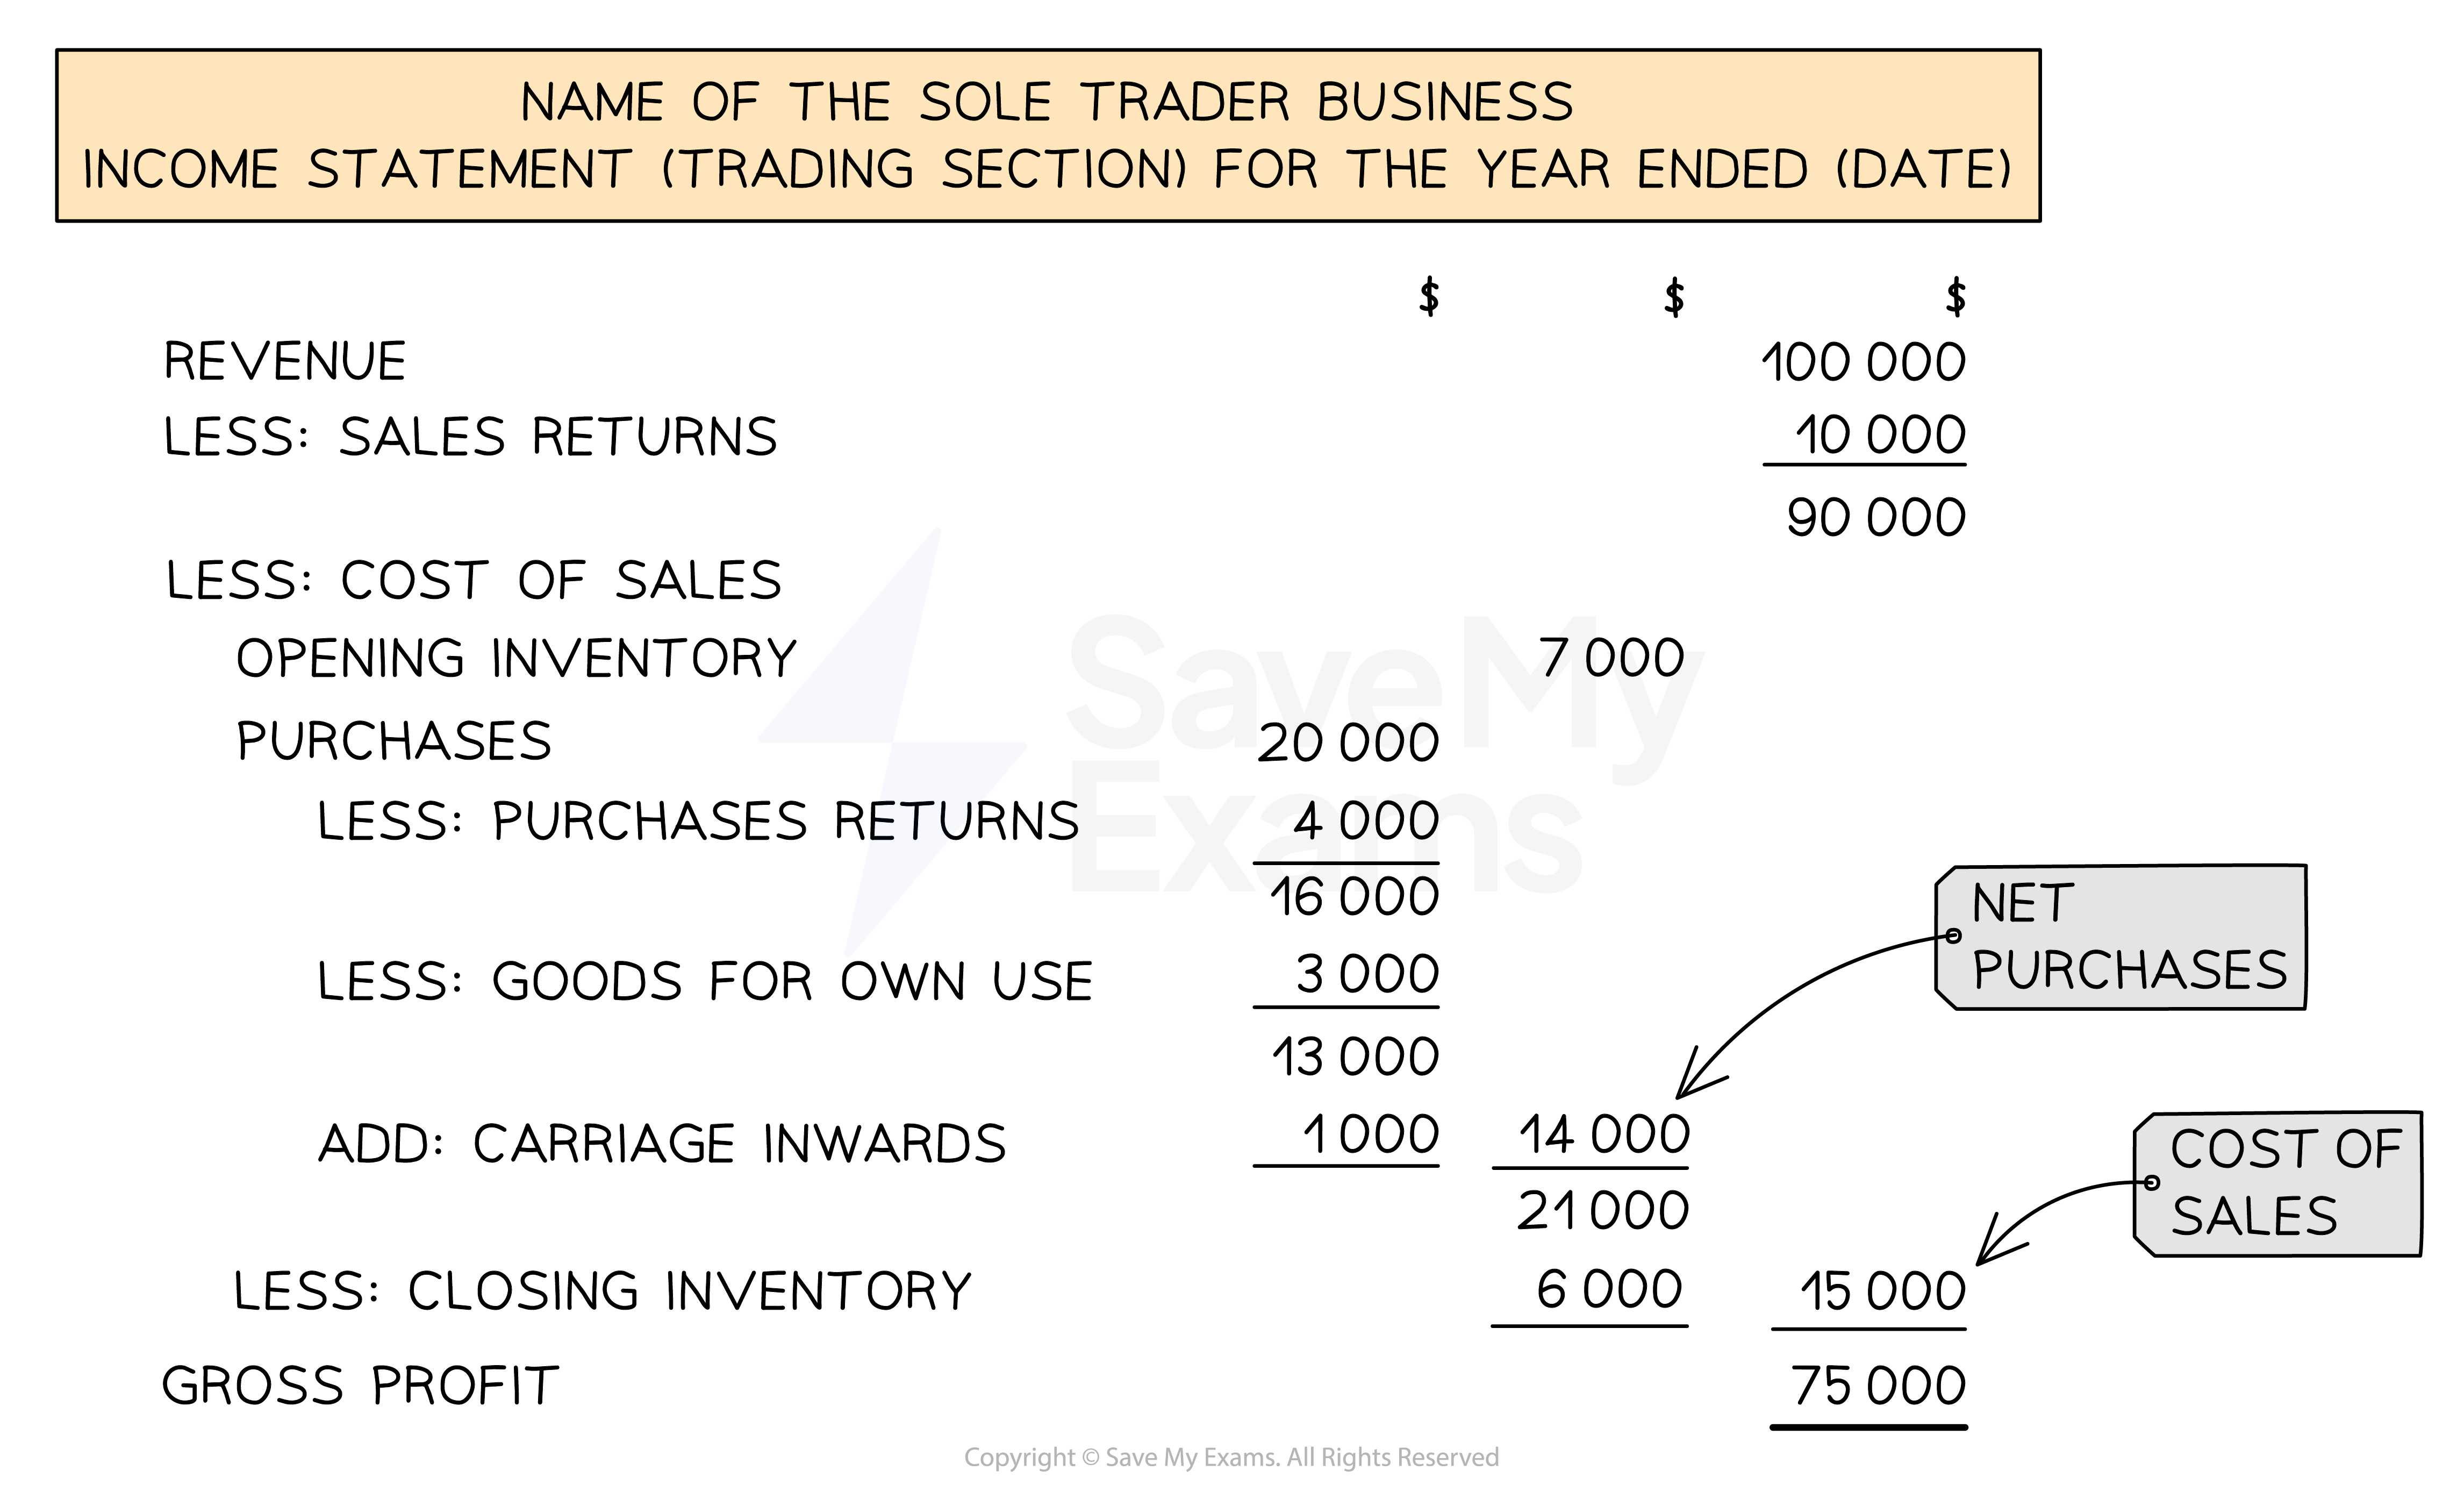
The layout of the trading section of an income statement
Exam Hint In general, you move one column to the left if a calculation is needed that involves more than one item and a subtraction.
For example:
cost of sales involves a calculation and it is subtracted from the sales
- therefore the calculation is done in the middle column
It is normally only the calculation for the net purchases that is displayed in the far left column.
How do I complete the profit and loss section of an income statement?
-
STEP 1 Put the gross profit in the far right column
-
STEP 2 Total up any other incomes which increase the profit for the year such as
- Discount received
- Other income received
- Recovery of irrecoverable debts
- Profit on sale of non-current asset
-
STEP 3 Total up any other expenses which decrease the profit for the year such as
- Discount allowed
- Carriage outwards
- Irrecoverable debts written off
- Depreciation of non-current assets
- Loss on sale of non-current assets
- Sundry expenses
- Other expenses
-
STEP 4 Calculate the profit or loss for the year
- Gross profit
- Add other income
- Less other expenses
-
If the final value is a negative
-
Put brackets around the value
-
This means it is a loss not a profit
- E.g. (500) represents a loss of $500
-
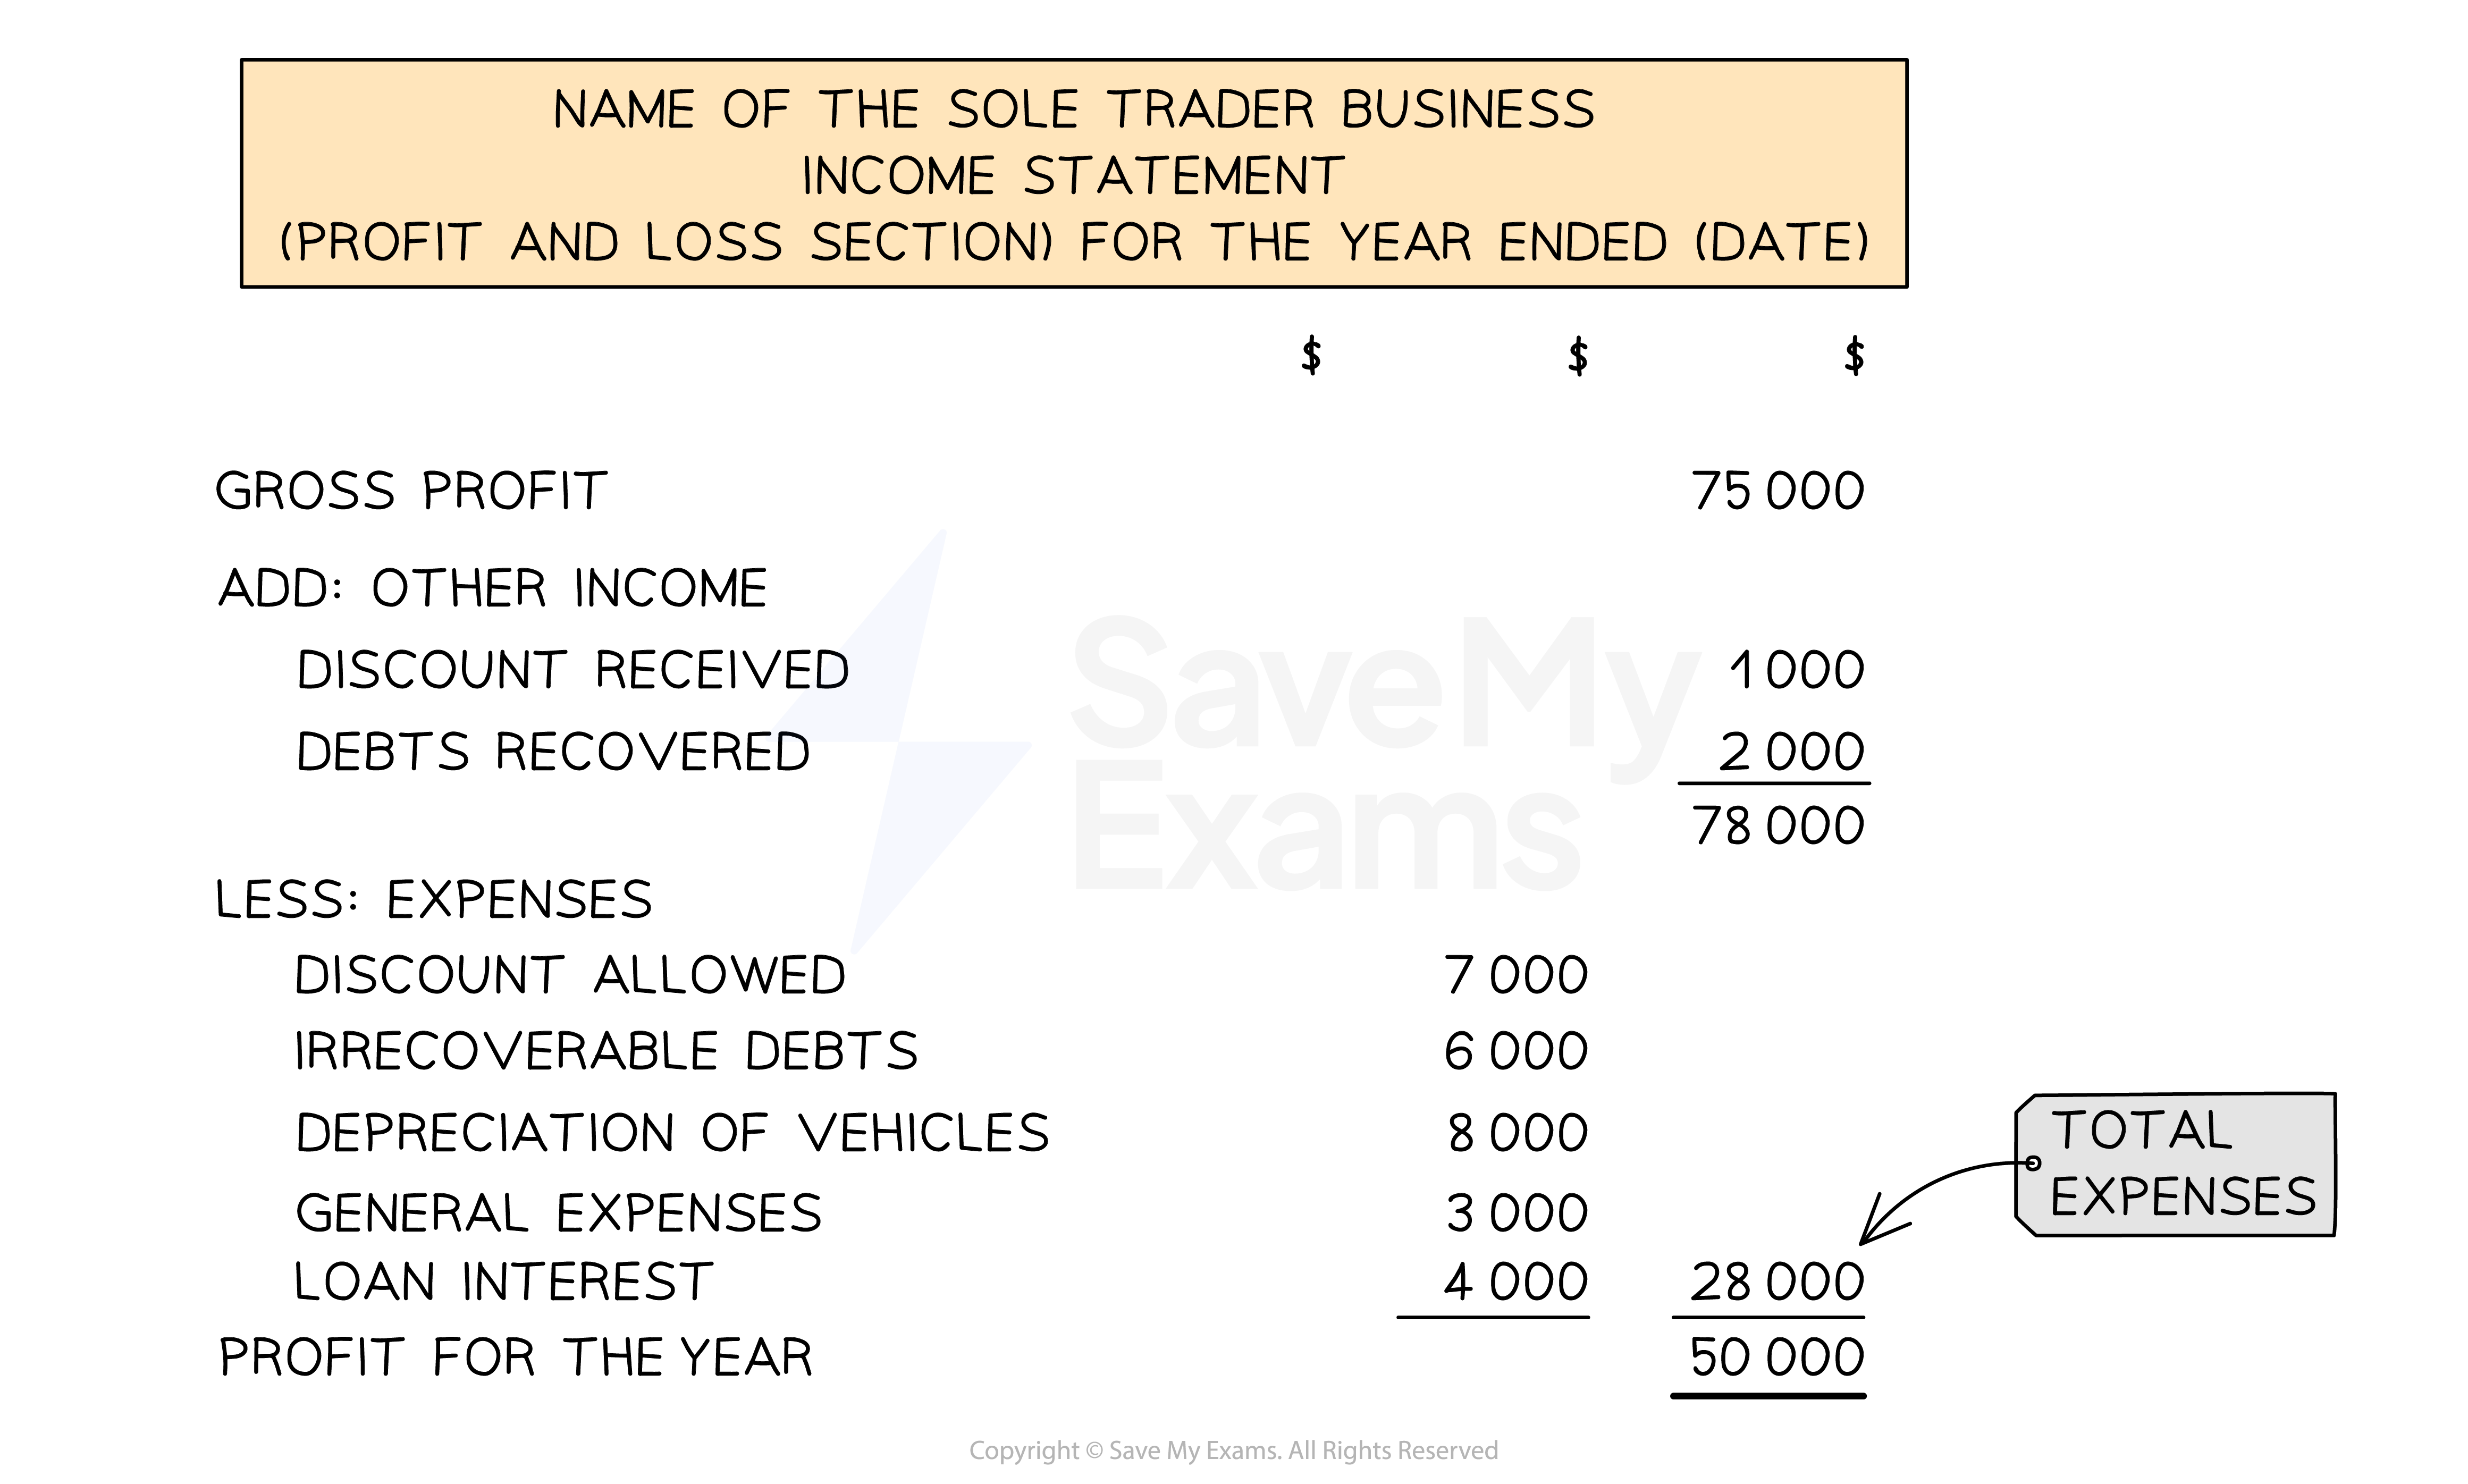
The layout of the profit and loss section of an income statement
Exam Hint The items for the other income can be put in the far right column as they are added to the gross profit. However, if you prefer you can put them in the middle column, find the total and put that in the far right column. Whereas the expenses need to go in the middle column because the total is subtracted from the previous figure in the far right column.
What is operating profit?
- Operating profit is also known as profit from operations
- It is the profit for the year before subtracting the loan interest
- Some businesses show this in the profit and loss section of their income statement
- If a business does not have finance costs then profit from operations is the same as profit for the year
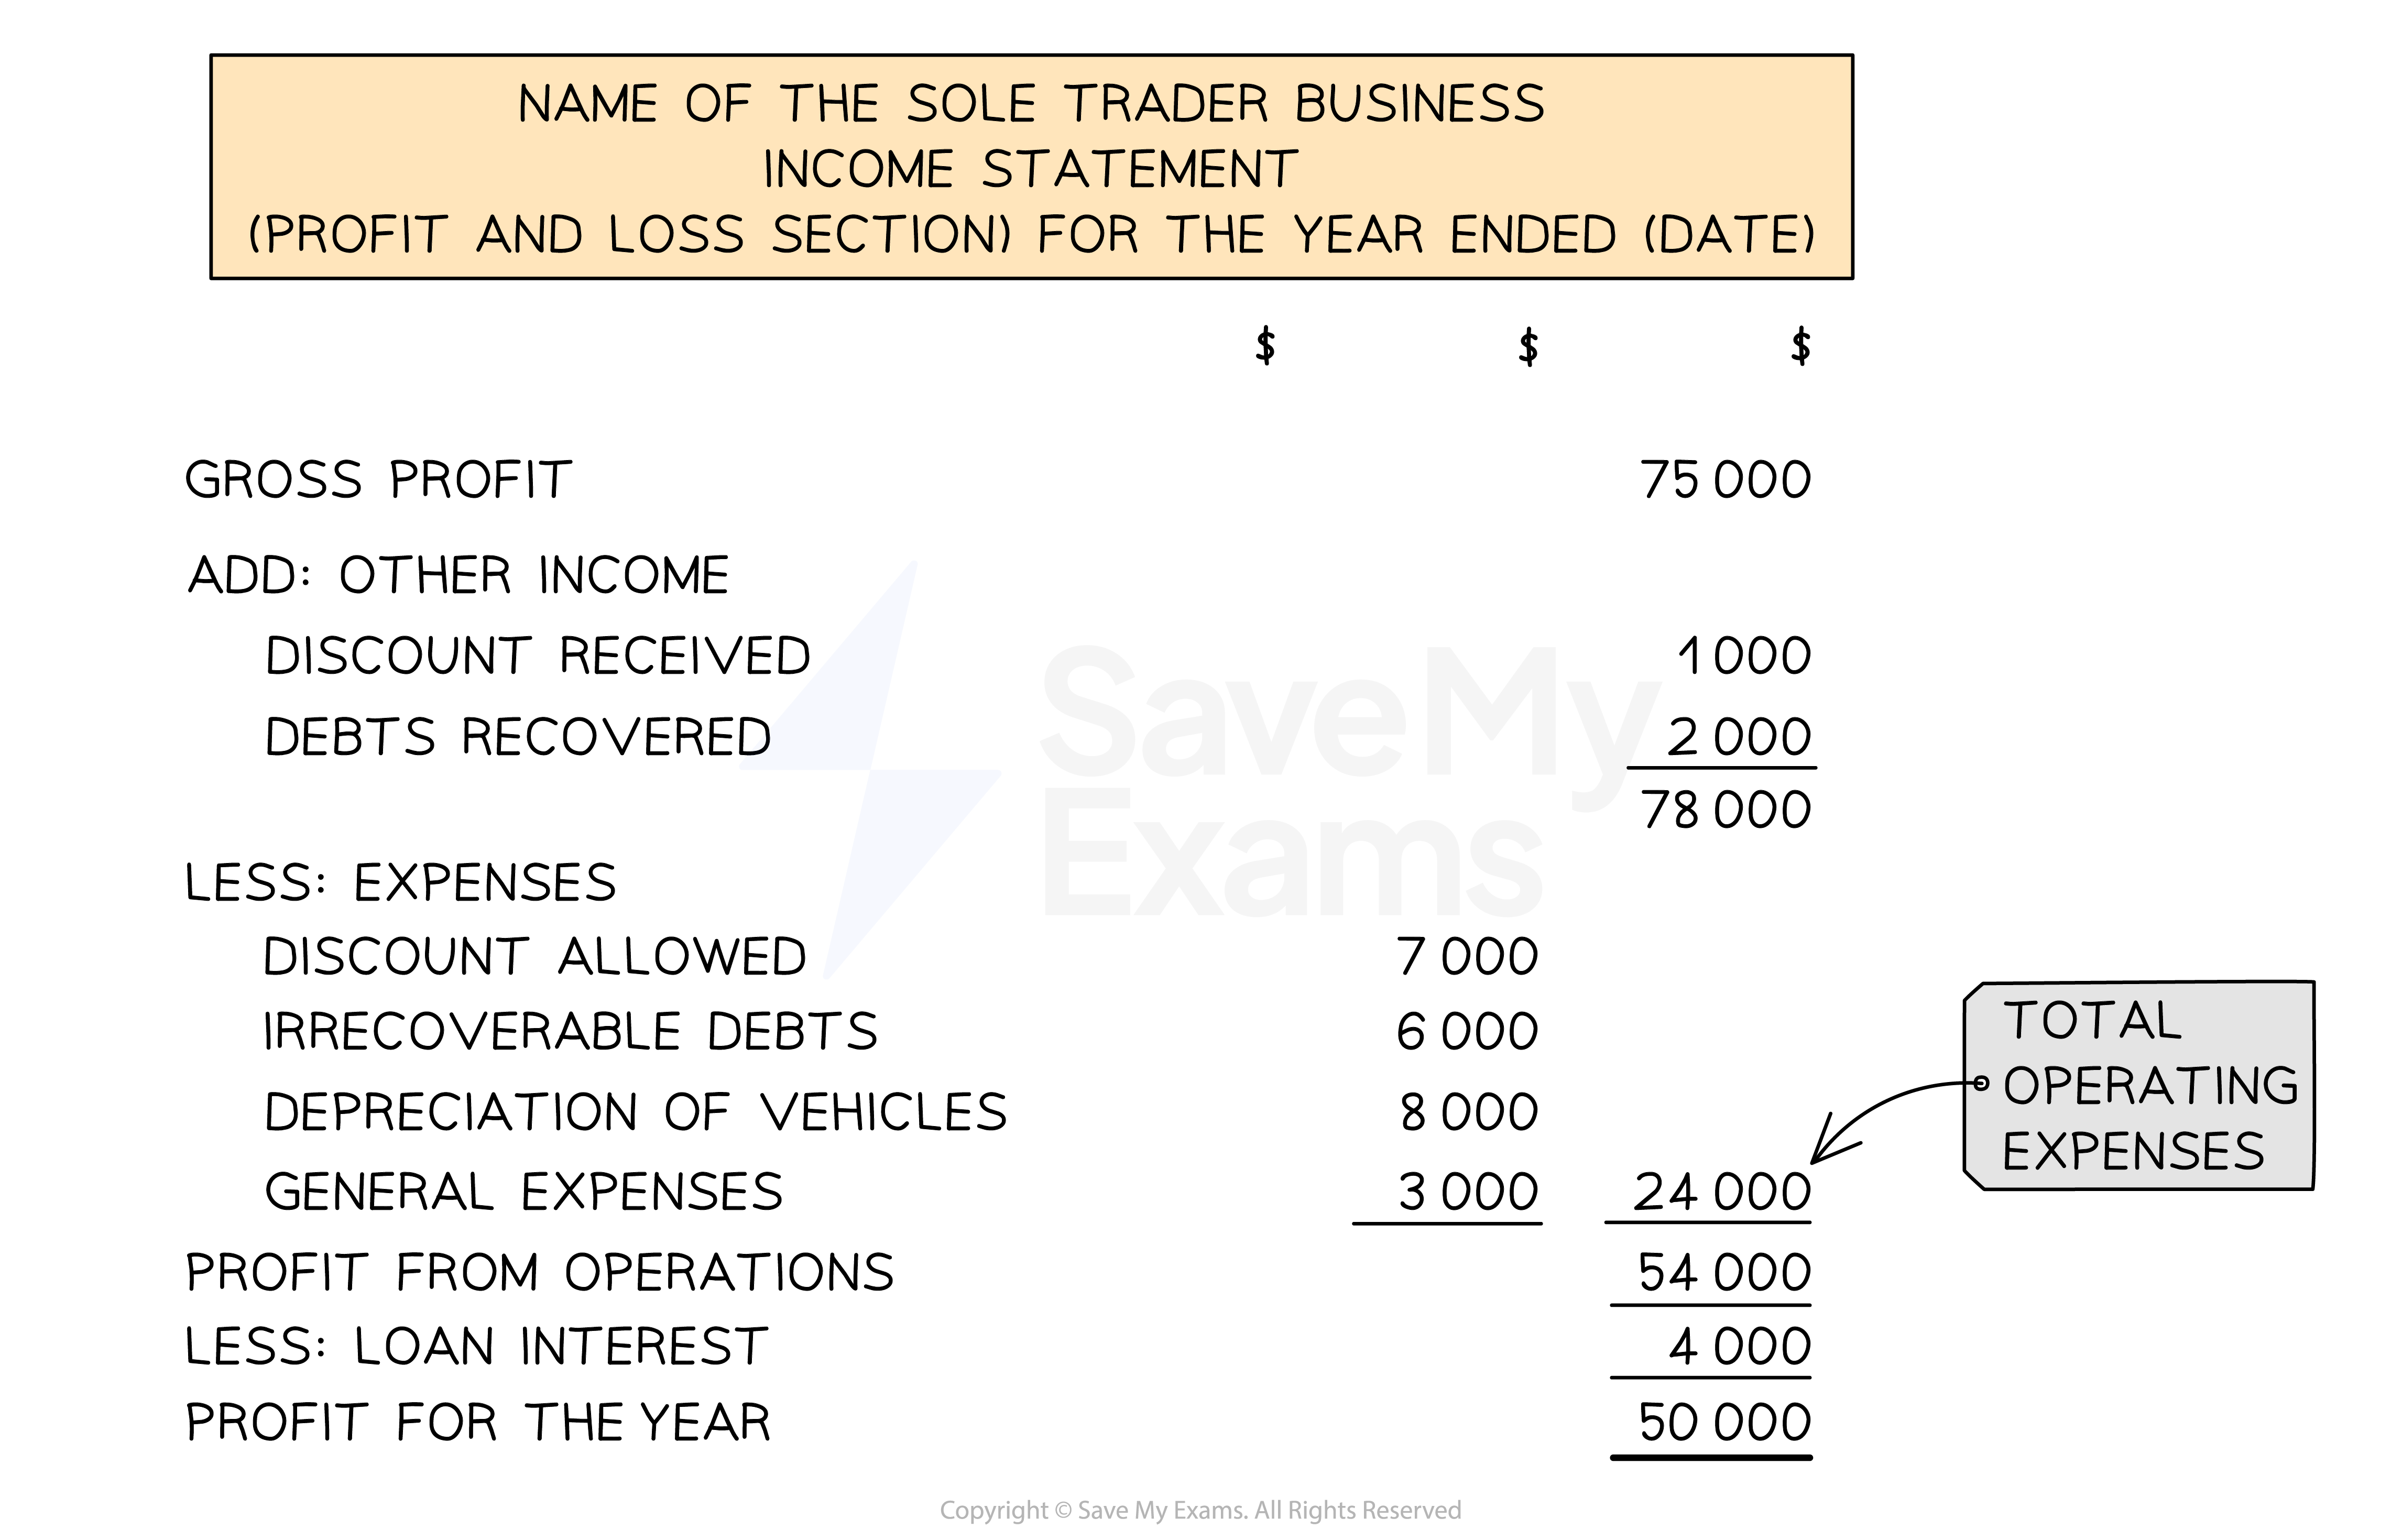
The layout of the profit and loss section of an income statement including profit from operations
How is the income statement of a trading business created?
-
The income statement of a trading business contains both the
- Trading section
- Profit and loss section
-
The gross profit links the two sections together
- You do not need to state this value twice
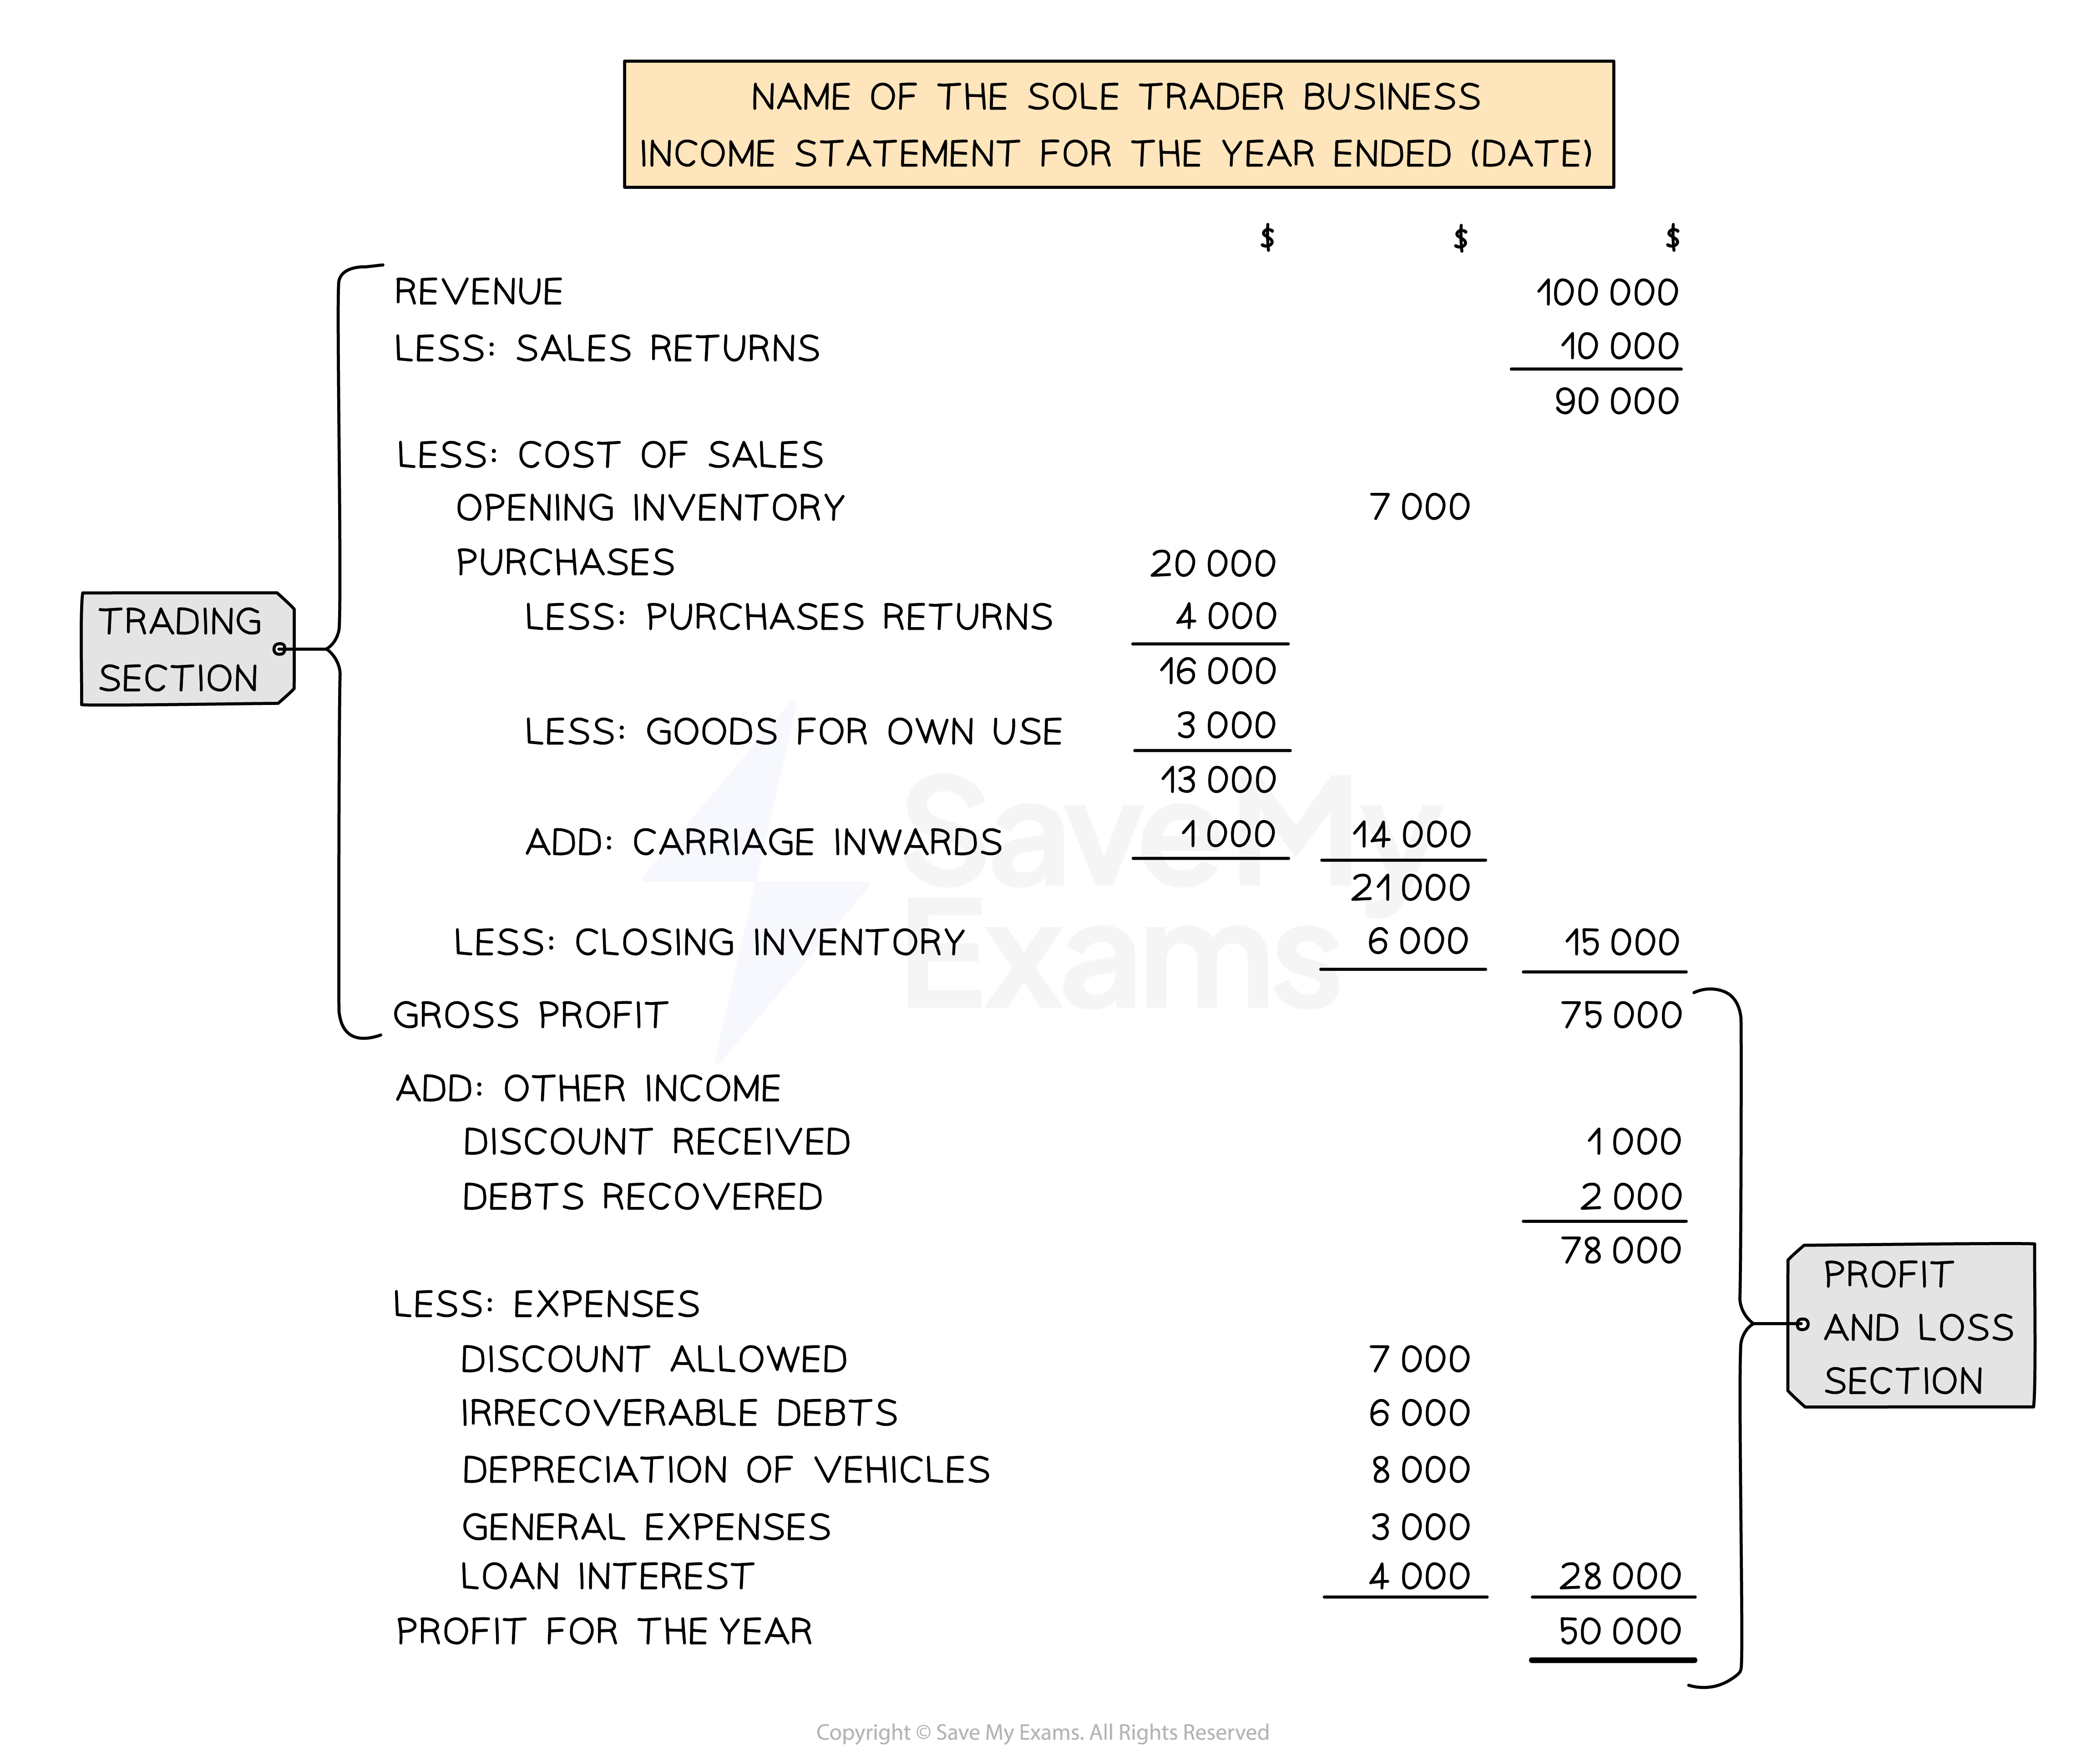
The layout of the income statement
Exam Hint The exam might give you the information in a trial balance along with additional information underneath. Identify items from the trial balance that would appear on the income statement. You might find it helpful to annotate with IS to differentiate from those which would appear on the statement of financial position.
Worked Example The following trial balance has been extracted by the book-keeper of Ali Baba, a wholesaler of school supplies, at 31 December 2023.
Debit
$**Credit
$Trade receivables 25 325 Trade payables 20 684 Capital 40 000 Bank 2 083 Rent and rates 11 862 Electricity 3 054 Telephone 2 695 Salaries 56 891 Vehicles 23 250 Office equipment 8 500 Vehicle expenses 13 855 Drawings 16 275 Discount allowed 478 Discount received 591 Purchases 139 960 Revenue (Sales) 258 258 Inventory at 1 January 2023 19 471 321 616 321 616 Additional information:
- Inventory at 31 December 2023 is valued at $15 075
- The vehicles and office equipment were purchased during the year and Ali Baba does not charge depreciation in the year of purchase
Prepare an income statement for Ali Baba for the year ended 31 December 2023.
Answer:
- Identify which items appear on the income statement by labelling them as IS
- Add an extra row for the closing inventory
Debit
$Credit
$Income statement? Trade receivables 25 325 Trade payables 20 684 Capital 40 000 Bank 2 083 Rent and rates 11 862 IS Electricity 3 054 IS Telephone 2 695 IS Salaries 56 891 IS Vehicles 23 250 Office equipment 8 500 Vehicle expenses 13 855 IS Drawings 16 275 Discount allowed 478 IS Discount received 591 IS Purchases 139 960 IS Revenue (Sales) 258 258 IS Inventory at 1 January 2023 19 471 IS 321 616 321 616 Inventory at 31 December 2023 15 075 IS Complete the income statement using the formula to help:
Complete the trading section to find the gross profit
Revenue (sales)
Minus cost of sales
- Opening inventory
- Plus purchases
- Minus closing inventory
Complete the profit and loss section to find the profit for the year
- Gross profit
- Plus other income
- Minus expenses
Final answer:** Ali Baba
Final answer: Income Statement for the year ended 31 December 2023 **Final answer:****$ Final answer: $ Final answer:** Revenue ** Final answer:** ** Final answer:** 258 258 ** Final answer: Less: Cost of sales Final answer:** ** Final answer:** ** Final answer:** Opening inventory ** Final answer:** 19 471 ** Final answer:** ** Final answer:** Purchases ** Final answer: 139 960** Final answer: Final answer: Final answer: 159 431 Final answer: Final answer: Less: Closing inventory Final answer: 15 075 Final answer: 144 356 ** Final answer:** Gross Profit ** Final answer:** ** Final answer:** 113 902 ** Final answer:** Add: Other income ** Final answer:** ** Final answer:** ** Final answer:** Discount received ** Final answer:** ** Final answer:** 591 ** Final answer:** ** Final answer:** ** Final answer:** 114 493 ** Final answer:** Less: Expenses ** Final answer:** ** Final answer:** ** Final answer:** Discount allowed ** Final answer:** 478 ** Final answer:** ** Final answer:** Rent and rates ** Final answer:** 11 862 ** Final answer:** ** Final answer:** Electricity ** Final answer:** 3 054 ** Final answer:** ** Final answer:** Telephone ** Final answer:** 2 695 ** Final answer:** ** Final answer:** Salaries ** Final answer:** 56 891 ** Final answer:** ** Final answer:** Vehicle expenses ** Final answer:** 13 855 ** Final answer: 88 835** Final answer: Profit for the year Final answer: Final answer: 25 658
Income statement for service businesses
How is the income statement of a service business created?
-
The income statement of a service business does not have a trading section
- Because they do not buy or sell goods
- Therefore there will not be a gross profit
-
The income statement for a service business only contains the profit and loss section
- Therefore the income statement will start with the income received
How do I complete an income statement for a service business?
-
STEP 1 Total up any income such as:
- Commission
- Rent
- Other income received
-
STEP 2 Total up any expenses such as:
- Wages
- General expenses
- Operating expenses
-
STEP 3 Calculate the profit or loss for the year
- The total income minus the total expenses
Worked Example Sherwin operates a taxi service and has provided the following information at the end of the financial year on 31 October 2023. Prepare the income statement for Sherwin’s Taxi Service for that period.
$ General expenses 9 250 Insurance 3 200 Printing and stationery 1 560 Income from taxi fares 85 250 Motor expenses 15 750 Loan interest 1 200 Answer:
- Start with the income
- Subtract the expenses
- Calculate the profit for the year
Final answer: Sherwin’s Taxi Service
Final answer: Income Statement for the year ended 31 October 2023Final answer: $** Final answer: $ Final answer: Income from taxi fares Final answer: 85 250 Final answer: Less: Expenses General expenses Final answer: 9 250 Insurance Final answer: 3 200 Printing and stationery Final answer: 1 560 Motor expenses Final answer: 15 750 Loan interest 1 200 Final answer:** 30 960 ** Final answer: Profit for the year Final answer: 54 290 You can also state the profit from operations.
- Start with the income
- Subtract the operating expenses
- Calculate the profit from operations
- Subtract the loan interest
- Calculate the profit for the year
Final answer: Sherwin’s Taxi Service
Final answer: Income Statement for the year ended 31 October 2023Final answer:****$ Final answer: **$ Final answer: Income from taxi fares Final answer: 85 250 Final answer: Less: Expenses General expenses 9 250 Insurance 3 200 Printing and stationery 1 560 Motor expenses 15 750 29 760 Final answer: Profit from operations 55 490 Final answer: Less: Loan interest 1 200 Final answer: Profit for the year 54 290
Was this revision note helpful?
Build on this topic