Accounts for Clubs & Societies (Cambridge International IGCSE Accounting)
Clubs & societies
What types of businesses are clubs and societies?
- Clubs and societies are classed as non-trading organisations
- These types of businesses provide a service or facility for a fee called a subscription
- They do not operate with the sole aim of making a profit
What financial statements are prepared for clubs and societies?
-
Clubs and societies do not always keep a full set of accounting records
-
Their main accounting records tend to be
-
A receipts and payments account
- This is a simple cash book
-
Trading sections of income statements for each one of any trading activities
- Such as a café or a shop
- These are prepared in the same way as for sole traders
-
An income and expenditure account
- This shows the sources of income and expenses of the organisation
- This is equivalent to the income statement for a sole trader
-
A subscription account
- This calculates the fees that should have been received from members during the year
-
A statement of financial position
- This is prepared in a similar way to that of sole traders
-
Income statement for clubs & societies
Why might clubs and societies prepare income statements?
- Income statements are prepared when the club or society involves a trading activity which buys and sells goods to raise extra money
- A separate income statement is prepared for each trading activity
- The profits or losses made from the trading activities are transferred to the income and expenditure account
What is included in the income statements for trading activities?
- The income statement is prepared similarly to the trading section of the income statement of any other business
- The main difference is that the gross profit is not always calculated
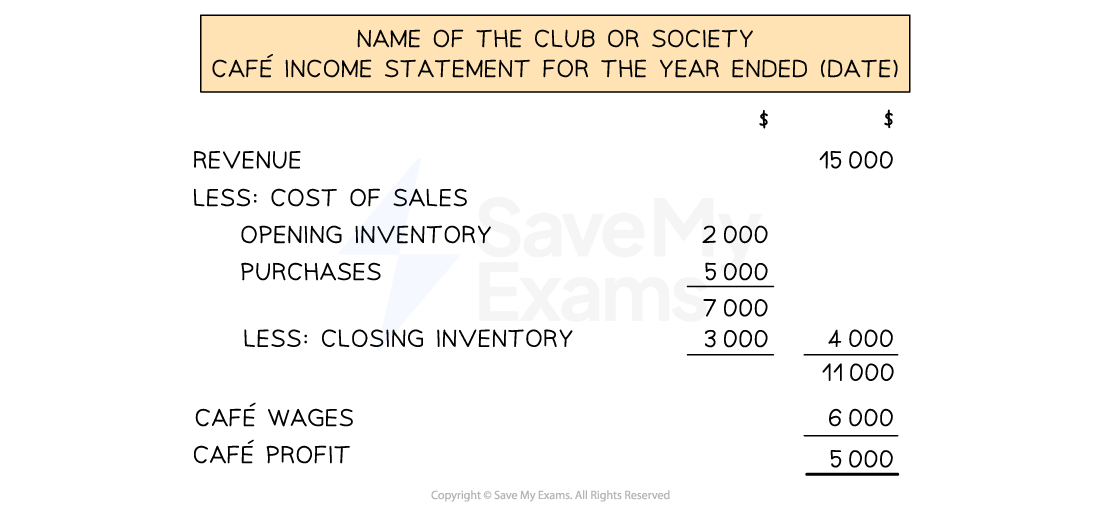
Layout of an income statement for a trading activity of a club or society
Worked Example Paramount Badminton Club owns badminton courts. It also operates a shop where it sells refreshments and badminton equipment. Shop sales are on a cash basis and purchases made for the shop are on credit.
The treasurer of the club provided the following information.
1 January 2023 31 December 2023 $ $ Subscriptions in advance 2 200 2 050 Subscriptions in arrears 6 515 6 850 Total shop trade payables 5 375 5 950 Shop inventory 3 600 3 200 Balance at bank 360 220 Other information provided for the year ended 31 December 2023:
Shop sales 48 120 Subscriptions received during the year 38 700 Shop purchases 36 200 Shop purchases returns 2 710 Shop wages 4 820 Wages for the club caretakers 2 650 Insurance for the club 3 640 Bank charges for the club 80 Telephone for the club 380 Advertising for the club 460 Depreciation of equipment for the club 520 Prepare the shop income statement for the year ended 31 December 2023.
Answer:
Only income and expenses related to the shop appear on the shop income statement
- Do not include anything that is for the club in general such as subscriptions
Include all the expenses in the cost of sales
Final answer: Paramount Badminton Club
Final answer: Shop Income Statement for the year ended 31 December 2023Final answer: $** Final answer: $ Final answer: Shop sales Final answer: 48 120 Final answer: Less: Cost of sales Final answer:** Opening Inventory ** Final answer: 3 600 Final answer:** Purchases ** Final answer: 36 200 Final answer: 39 800 Final answer:** Less: Purchases returns ** Final answer: 2 710 Final answer: 37 090 Final answer:** Less: Closing inventory ** Final answer: 3 200 Final answer: 33 890 Final answer:** ** Final answer: 14 230 Final answer:** Shop wages Final answer: 4 820 Final answer: Shop profit Final answer: 9 410
Was this revision note helpful?
Build on this topic