Nationalisation & Privatisation (Cambridge International A-Level Economics)
What is nationalisation and privatisation?
- Nationalisation is the transfer of privately owned firms or assets into public (government) ownership
- Privatisation is the transfer of state-owned firms or assets into private ownership
- Both policies reflect fundamentally different views about the role of government in the economy - a direct application of the key concepts of the role of government and the issues of equality and equity
- The central evaluative tension is between allocative and equity objectives (favouring nationalisation) and productive and dynamic efficiency objectives (favouring privatisation)
Nationalisation
-
Governments nationalise industries when private ownership leads to market failure that cannot be adequately corrected through regulation alone
-
The most important economic justification is the natural monopoly argument:
-
Some industries have very high fixed costs and declining average costs over the relevant range of output
- One firm can supply the entire market at lower average cost than two or more firms
-
A private natural monopoly produces where MR = MC, setting price above marginal cost
- This is allocatively inefficient
-
Nationalisation allows the government to set price closer to marginal cost, moving output towards the socially optimal level
-
-
Other justifications:
- Equity: ensuring universal access to essential services regardless of income or location
- Strategic industries: retaining control over industries critical to national security or economic development
Case Study Rail Nationalisation in the UK
The context
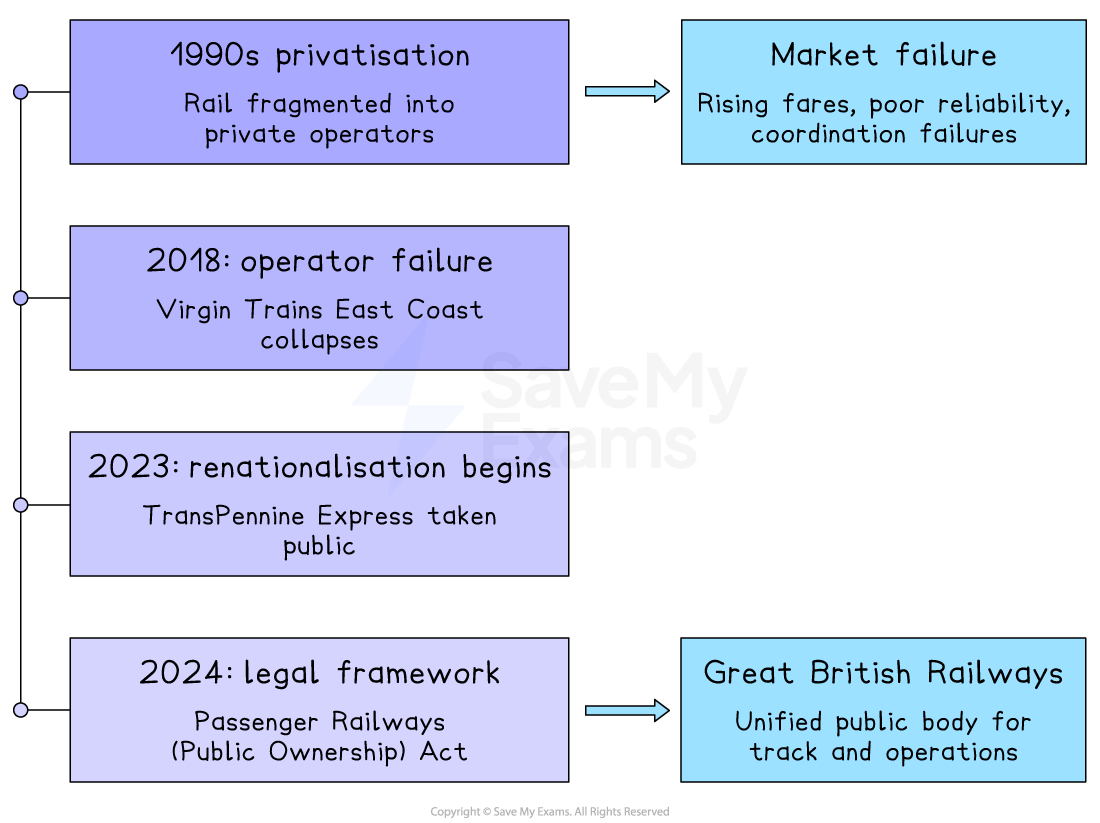
Renationalisation in UK rail
The UK privatised its national rail network in the 1990s, fragmenting it into multiple private operating companies
Persistent problems followed - rising fares, overcrowding, unreliable services and several high-profile operator collapses, most notably the failure of Virgin Trains East Coast in 2018 and the collapse of Northern Rail during the COVID-19 pandemic
Actions taken
- The UK government brought TransPennine Express (2023) and Avanti West Coast under public control
- The Passenger Railway Services (Public Ownership) Act 2024 provided the legal framework to return all remaining private operators to public ownership as their contracts expire
- Great British Railways was established as a new public body to manage both track and operations under unified public ownership
Outcomes
- It is too early to draw firm conclusions, as renationalisation is still in progress
- Proponents argue unified ownership will reduce coordination failures and improve service reliability
- Critics warn that without competitive pressure, X-inefficiency will rise and taxpayer costs will increase significantly
Evaluating nationalisation
| Advantages | Disadvantages |
|---|---|
| - Corrects natural monopoly failure - government can set price at MC rather than the profit-maximising price, improving allocative efficiency | - X-inefficiency - without competitive pressure, state enterprises tend to operate above minimum cost |
| - Equity - ensures universal access to essential services regardless of income or location | - Political interference - pricing and investment decisions may be driven by political rather than economic objectives |
| - Long-term investment - allows infrastructure investment with long payback periods that private firms would avoid | - Fiscal burden - loss-making state enterprises require ongoing subsidies, creating an opportunity cost |
| - Prevents private monopoly exploitation - removes the incentive to restrict output and raise prices | - Lack of innovation - absence of competitive pressure reduces incentives for dynamic efficiency |
Privatisation
-
Governments privatise state enterprises when they judge that private ownership will improve efficiency through competitive pressure and the profit motive
-
The economic case rests on:
- Productive efficiency — private firms face a profit motive and competitive pressure to minimise costs
- Dynamic efficiency — stronger incentives to innovate and adopt new technology
- Reducing the fiscal burden — raises one-off revenue and removes ongoing subsidies to loss-making enterprises
Case Study Partial Privatisation of Saudi Aramco
The context
Saudi Aramco is the world's largest oil company, wholly owned by the Saudi state since 1980
As part of Vision 2030, Crown Prince Mohammed bin Salman's programme to reduce oil dependence, the government announced plans to partially privatise Aramco through a public share offering.
Actions taken
- In December 2019, Aramco launched its IPO on the Tadawul (Saudi stock exchange), selling approximately 1.5% of shares to domestic and regional investors and raising $25.6 billion — the largest IPO in history at the time
- A further 0.5% stake was sold in June 2024, raising an additional $11.2 billion
- The Saudi government retained approximately 98% ownership, maintaining strategic control
Outcomes
The partial privatisation raised substantial government revenue to fund Vision 2030 whilst stopping well short of full privatisation
- Critics argue the limited share sale made little difference to operational efficiency since the state retained overwhelming control.
The case illustrates that privatisation exists on a spectrum
- Governments frequently prioritise strategic control over the productive efficiency gains that full private ownership might deliver
Evaluating privatisation
| Advantages | Disadvantages |
|---|---|
| - Productive efficiency - profit motive reduces X-inefficiency | - Natural monopoly problem - without effective regulation, privatisation transfers monopoly power from public to private hands |
| - Dynamic efficiency - stronger incentives to innovate | - Equity concerns - private firms may reduce services to unprofitable areas or raise prices for low-income consumers |
| - Raises government revenue - one-off proceeds reduce public debt | - Short-termism - private firms may prioritise short-run profit over long-run infrastructure investment |
| - Reduces fiscal burden - removes ongoing subsidies to loss-making enterprises | - Regulatory requirements - effective privatisation requires strong independent institutions that may not exist in lower-income economies |
The regulation problem with privatisation
- Privatisation of a natural monopoly only improves outcomes if accompanied by effective independent regulation
- Without regulation, a privatised natural monopoly remains allocatively inefficient, restricting output and charging prices above marginal cost
- Regulators themselves face the risk of regulatory capture, undermining their independence
- In lower-income economies where regulatory institutions are weak, privatisation may therefore worsen rather than improve outcomes
Nationalisation vs privatisation: key comparison
| Feature | Nationalisation | Privatisation |
|---|---|---|
| Primary objective | - Allocative efficiency, equity | - Productive and dynamic efficiency |
| X-inefficiency risk | - Higher | - Lower |
| Natural monopoly | - Can set P = MC | - Risk of exploitation without regulation |
| Equity | - Generally pro-equity | - May reduce access for low-income consumers |
| Key risk | - Political interference, X-inefficiency | - Regulatory failure, short-termism |
Exam Hint The strongest evaluative point for privatisation is the natural monopoly regulation problem. Privatisation only improves allocative efficiency if accompanied by effective independent regulation.
Always link to the efficiency and inefficiency key concept: nationalisation targets allocative efficiency and equity; privatisation targets productive and dynamic efficiency - these objectives are often in tension.
The best answers acknowledge that optimal policy depends on institutional context: privatisation works well where strong regulatory institutions exist; nationalisation may be preferable where they do not.
Was this revision note helpful?
Build on this topic