Schedule of Non-current Assets (Cambridge International A-Level Accounting)
Spec point — how to prepare for a limited company in line with the relevant international accounting standards and legal requirements: – schedule of non-current assets
Schedule of non-current assets
What is a schedule of non-current assets?
-
A schedule of non-current assets is a note to the statement of financial position
- It is required under IAS 16
-
It shows the movement in cost or valuation and accumulated depreciation for each class of non-current asset
-
It has a column for each class of non-current asset and a column for the total
- Classes include: land and buildings, plant and machinery, motor vehicles, etc
How do I prepare a schedule of non-current assets?
Cost section
-
Start with the balances at the start of the year
-
Add any additions or acquisitions
- These are the non-current assets that the business has gained during the year
-
Subtract any disposals
-
Add or subtract any amounts due to revaluations
-
This gives you the balances at the end of the year
Accumulated depreciation section
-
Start with the balances at the start of the year
-
Add the depreciation charge for the year
- Check whether assets sold or purchased during the year are charged depreciation
-
Subtract the accumulated depreciation for disposed assets
-
Subtract the accumulated depreciation for revalued assets
-
This gives you the balances at the end of the year
Carrying value section
-
State the carrying values at the start of the year
-
State the carrying values at the end of the year
- They should equal the closing balances for the cost minus the closing balances for the accumulated depreciation
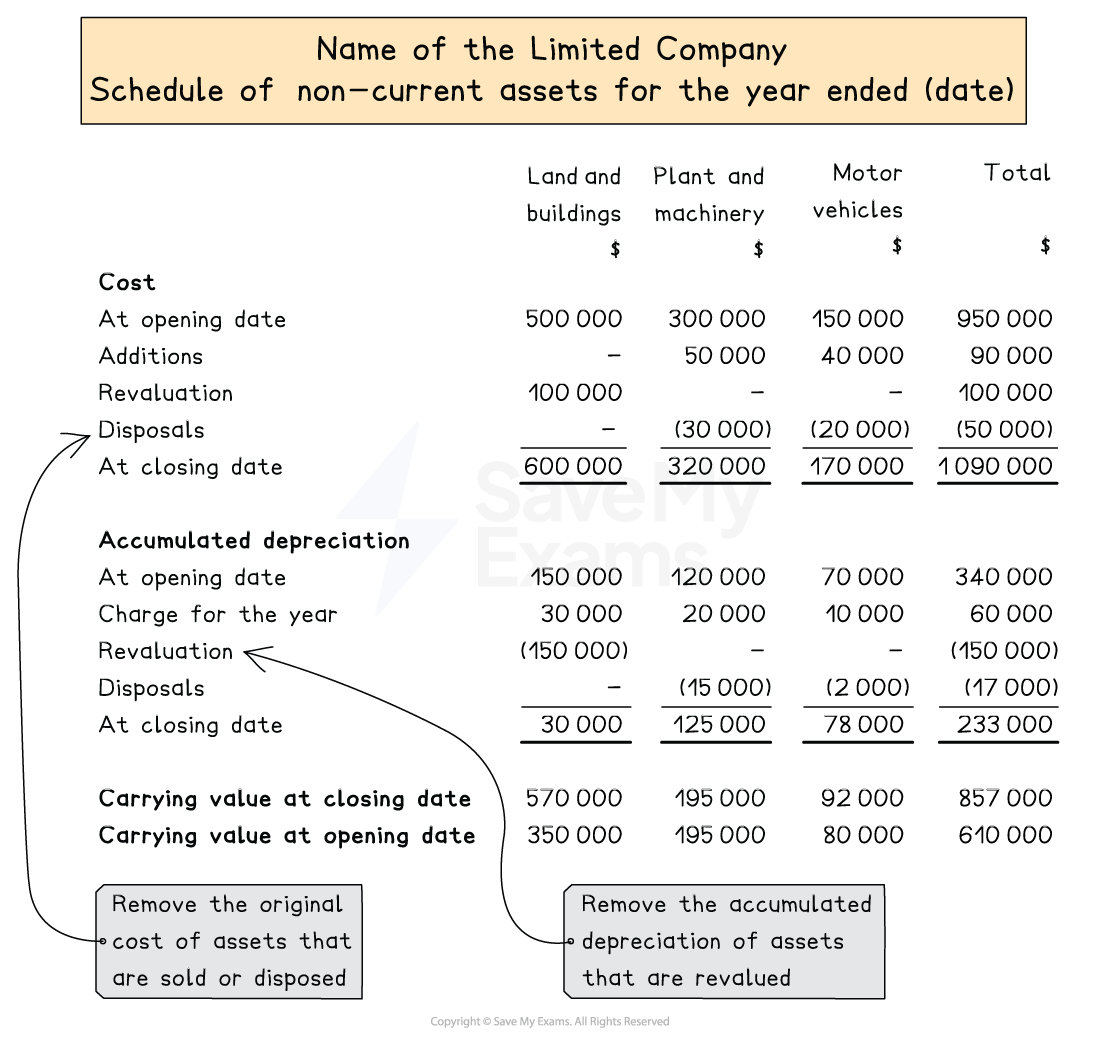
Layout of a schedule of non-current assets
Actions for each transaction
| Event | Cost section | Accumulated depreciation section |
|---|---|---|
| Addition (purchase) | Add the cost | No entry |
| Disposal | Deduct the original cost | Deduct the accumulated depreciation |
| Revaluation (upward) | Add the increase in value | Deduct any existing accumulated depreciation |
| Revaluation (downward) | Deduct the decrease in value | Deduct any existing accumulated depreciation |
| Depreciation charge for the year | No entry | Add the charge for the year |
Exam Hint When an asset is revalued, the existing accumulated depreciation on that asset is eliminated (deducted) from the accumulated depreciation section. After revaluation, the asset sits at its new fair value with a clean slate of zero accumulated depreciation.
Worked Example The cost section and accumulated depreciation section of Omega plc’s schedule of non-current assets at 31 December 2024 are as follows:
Land and buildings
$**Plant and machinery
**$Motor vehicles
$Cost At 1 January 2024 300 000 210 000 140 000 Additions 100 000 40 000 - At 31 December 2024 400 000 250 000 140 000 Accumulated depreciation At 1 January 2024 70 000 85 000 56 000 Charge for the year 10 000 33 000 28 000 At 31 December 2024 80 000 118 000 84 000 The following information has been provided for the year ended 31 December 2025:
The 'Land and buildings' balance at 31 December 2024 consists of Land costing $200 000 and Buildings costing $200 000. On 1 January 2025, the directors decided to revalue the land upwards to $290 000.
On 1 April 2025, a new machine was purchased at a cost of $55 000.
During the year, a motor vehicle which had originally cost $30 000 was sold for $11 000. There was a $1 000 loss on disposal.
The company's depreciation policy is as follows:
- Land: No depreciation is charged.
- Buildings: 5% per annum using the straight-line method.
- Plant and machinery: 20% per annum using the reducing balance method.
- Motor vehicles: 20% per annum using the straight-line method.
- A full year's depreciation is provided in the year of acquisition and none is provided in the year of disposal.
Prepare the schedule of non-current assets for Omega plc for the year ended 31 December 2025, suitable for use as a note to the financial statements.
Answer:
Calculate the carrying values at 31 December 2024
Land and buildings
$**Plant and machinery
**$Motor vehicles
$Cost 400 000 250 000 140 000 Accumulated depreciation 80 000 118 000 84 000 Carry value 320 000 132 000 56 000 Calculate the increase in the value of the land due to the revaluation
$290 000 - $200 000 = $90 000
Calculate the accumulated depreciation of the sold vehicle
- Calculate the net book value by adding the loss to the sale proceeds
$11 000 + $1 000 = $12 000
- Subtract this from the original cost
$30 000 - $12 000 = $18 000
Calculate the depreciation charge for the year
- Buildings
5% × $200 000 = $10 000
Plant and machinery
- Add the purchase price to the carrying value from the start of the year
20% × ($132 000 + $55 000) = $37 400
Motor vehicles
- Subtract the cost of the sold vehicle
20% × ($140 000 - $30 000) = $22 000
Omega plc
Schedule of Non-Current Assets for the year ended 31 December 2025
Land and buildings
$**Plant and machinery
$Motor vehicles
$Total
$Cost or Valuation At 1 January 2025 400 000 250 000 140 000 790 000 Revaluation 90 000 - - 90 000 Additions - 55 000 - 55 000 Disposals - - (30 000) (30 000) At 31 December 2025 490 000 305 000 110 000 905 000 Accumulated Depreciation At 1 January 2025 80 000 118 000 84 000 282 000 Charge for the year 10 000 37 400 22 000 69 400 Disposals - - (18 000) (18 000) At 31 December 2025 90 000 155 400 88 000 333 400 Carrying Amount At 31 December 2025 400 000 149 600 22 000 571 600 At 31 December 2024 320 000 132 000 56 000 508 000
Was this revision note helpful?
Build on this topic